Telephone
02-77093611
Line
@fdlaw
address
17th Floor, No. 180, Section 2, Dunhua South Road, Da'an District, Taipei City
Telephone
02-77093611
Line
@fdlaw
address
17th Floor, No. 180, Section 2, Dunhua South Road, Da'an District, Taipei City


Two friends started a business together, each contributing 50%.
The beginning is the fairest.
However, when a real dispute arises within the company, a 50-50 equity structure can become one of the most difficult to handle.
Common scenarios include: the two shareholders have completely different views on the company's direction; neither can obtain a majority of support; each has their own people on the board of directors; bank accounts or seals require the cooperation of both parties; one party wants to continue operating while the other wants to leave; both parties feel that they should stay in the company; but there is no consensus on the share price.
Ultimately, the company may face the following problems: shareholders' meetings cannot be held; the board of directors cannot make decisions; important contracts are stalled; employees do not know whose advice to follow; and the company gradually loses assets and customers.
This is a typical example: Shareholder deadlock.
However, when truly dealing with shareholder deadlock, it's not enough to simply ask: "Who is right and who is wrong?"
Instead, we should ask: Should the company continue?
Who wants to stay?
Who wants to quit?
How is equity transferred?
How is the price calculated?
as well as: If they can't reach an agreement at all, what legal recourse is there?
While people often use the colloquial term "breaking up a partnership," the relationship between company shareholders is not a civil law partnership; the withdrawal of company shareholders should still be handled in accordance with the Company Law, articles of association, shareholder agreements, and equity transfer regulations.
Lawyers specializing in shareholder disputes and equity controversiesWe will first distinguish between exit, corporate governance, and accountability;Complete legal handling of shareholder disputes and corporate deadlockIt is also necessary to compare the shareholding and control structure.
uncertain.
A 50-50 split simply refers to the equity ratio.
The true control structure of a company also depends on: company type; articles of association; board seats; chairman of the board; voting rights; preferred shares; shareholders' agreement; banking authority; seals; and the actual management team.
For example, if each party holds 50% of the shares (%), but one party controls a majority of the board seats, the actual governance situation may not be completely symmetrical.
Conversely: if the equity is 50/50; the board of directors is also 1/1; and major decisions require the consent of both parties, it is easy to create a real business deadlock.
Therefore, the first step is not just to look at: 50% vs 50%.
Instead, it establishes: Equity structure diagram + governance diagram.
Different deadlocks require completely different legal tools.
For example:
No one could produce the desired voting result.
With equal seats on the board, important resolutions repeatedly fail to pass.
The two sides are vying for control of the company seal, bank, employees, or system.
One party is unwilling to invest any more funds, while the other party believes that the company still needs to increase its capital.
Both sides agree that someone should leave, but: Who should leave?
Who will buy it?
How much?
They couldn't reach an agreement at all.
First, you need to identify which type it is before you can choose the right tool.
This is not usually the correct way to understand it.
The investments made by shareholders in a company—capital contributions, share payments, and capital—are different legal relationships from loans made to the company.
If the initial investment was a genuine acquisition of equity, the company is not obligated to return the original investment to the shareholder simply because the shareholder now wants to leave.
Therefore: Investing 5 million yuan initially does not necessarily mean that you can demand a refund of 5 million yuan from the company when you withdraw from the investment.
The company may: have grown; have incurred losses; have substantial assets; or be heavily indebted.
The current value of the equity and the initial investment are two different questions.
In practice, the most direct way to exit is usually: Shareholder A sells their shares to: another shareholder; other existing shareholders; or a third party.
However, whether a transfer is possible must be confirmed first: Company type.
The rules for limited liability companies and joint-stock companies are not the same.
Limited liability companies have a strong personal element.
according toArticle 111 of the Company LawIn principle, for a shareholder to transfer all or part of their investment to another party, the following conditions must be met: the consent of more than half of the voting rights of the other shareholders.
If the person transferring the shares is a director, the threshold is even higher: more than two-thirds of the voting rights of the other shareholders are required to agree.
However, this does not mean that other shareholders can lock those who want to leave the company indefinitely simply by saying "I disagree".
becauseArticle 111It also stipulates that shareholders who disagree with the transfer have the right of first refusal; if those who disagree are unwilling to accept the transfer under the conditions, the law will have corresponding consequences.
Therefore, when a shareholder of a limited liability company withdraws, the most important question is not simply: "Does the other party agree?"
The following information should also be provided: the transferee; the price; the payment method; the transfer conditions; and whether other shareholders have acquired the shares.
This is a very typical problem.
For example: Product A: 50%; Product B: 50%.
A no longer wants to operate the business together and has found a third party willing to take over his investment for 10 million yuan.
At this point, we shouldn't just stop at: "Party B disagrees, so the sale cannot be made."
Should be based onArticle 111 of the Company LawThe specific transaction terms and conditions will be further confirmed, including: transfer notice; consent from other shareholders; preemptive rights; price; payment terms; amendment to the articles of association; and company registration.
A true exit strategy must take legal procedures and transaction terms into account.
In principle, joint-stock companies adopt the following policy: shares can be freely transferred.
Article 163 of the Company LawThe regulations stipulate that, unless otherwise provided by the Company Law, a company may not prohibit or restrict the transfer of shares through its articles of association.
Therefore, the problem with ordinary joint-stock companies is often not: "The law does not allow them to be sold."
Instead: Will anyone actually be willing to buy it?
Since non-listed companies lack a public market, even if they are legally transferable, they may still encounter problems such as: difficulty finding a buyer; lack of equity liquidity; the buyer's inability to obtain company information; disagreement on price; discounted control; and disputes over the value of minority shares.
Therefore, "shares can be transferred" does not mean that "shareholders can definitely withdraw."
A closed joint-stock company is essentially a privately held company whose share transfers are restricted.
Company law requires that restrictions on the transfer of relevant shares be stated in the articles of association.
Therefore, if the company is a closed joint-stock company, the general principle of "shares being freely transferable" cannot be directly applied to general joint-stock companies, and the analysis ends here.
First, you must see: what restrictions are actually imposed by the company's articles of association.
For example, it may involve: consent from other shareholders; preemptive rights; specific eligibility; specific transfer conditions.
Therefore, the first important document in every equity exit case is usually: Company Articles of Association.
Article 111 of the Company Law
The transfer of capital contributions requires the consent of other shareholders in accordance with the law. Shareholders who do not agree have the right of first refusal, and the threshold for obtaining the consent of directors to transfer their capital contributions is relatively high.
Common exit strategies include: transfer by other shareholders, transfer by a third party, and buyout by agreement.
Article 163 of the Company Law
In principle, shares can be transferred, but unlisted equity may lack buyers and market prices.
The company's acquisition of shares is subject to restrictions under Article 167 and other regulations.
Core: Articles of Association
Restrictions on share transfer should be stated in the articles of association. Before withdrawing, check the transfer restrictions, other shareholder rights, and the shareholders' agreement.
Article 356-1 of the Company LawandArticle 356-5 of the Company LawEstablish regulations to restrict the transfer of articles of association of closed-end companies.
A well-established shareholder agreement may stipulate in advance: preemptive rights; tag-along rights; drag-along rights; buy-sell options; exit in case of material default; equity handling upon founder's departure; valuation method; payment method; and deadlock resolution procedures.
If such clauses already exist, in the event of a shareholder dispute, the following should be confirmed first: whether the clauses are valid; whether the triggering conditions have been met; who can exercise them; how to give notice; and how the price is determined.
This is usually much easier than redesigning the exit mechanism after a dispute arises.
Further reading: Shareholder Agreement, Voting Rights and Exit Mechanism.
Can.
The real solution to many shareholder deadlocks is not a court ruling on who remains a shareholder, but rather: One side stays, the other leaves.
For example: A buys B; or: B buys A.
At the heart of this Buyout Negotiation, there are usually five questions: 1. Who has the ability to continue running the company?
2. Who really wants to stay?
3. What is the company's current value?
4. What positions and responsibilities will the departing person be relieved of?
5. Should the price be paid in one lump sum or in installments?
Simply talking about "how much is one share" is usually not enough.
Company law does not have a fixed formula that applies to the exit of all shareholders.
Equity valuation may need to consider: company net assets; cash; real estate; equipment; liabilities; accounts receivable; future profitability; customers; brand; technology; important contracts; litigation risks; taxes; related party transactions.
In some cases, further consideration is needed: Is this a controlling stake?
Or a minority stake?
Is the company highly dependent on a single founder?
Therefore, "how much was invested initially" is usually not the only valuation benchmark.
The two shareholders have a large price difference, and often it's not simply a matter of haggling over the price.
Rather, the two parties used fundamentally different information regarding the company's true value.
For example, one party argues that the company only has 1 million yuan in its accounts.
The other party argues that the company also has a large amount of: accounts receivable; inventory; intellectual property; related corporate interests; and unrecorded revenue.
At this point, directly asking, "How much are you willing to pay for my shares?" is unlikely to yield any results.
First, verify the following: financial statements; accounting books; bank flows; company assets; liabilities; major contracts; and related-party transactions.
If the company fails to provide the information, further assessments can be made regarding shareholder audits or inspector procedures.
Further reading: Shareholders' requests to inspect accounts, company's refusal to provide accounting books, and requests for inspectors can be found here.Shareholders' audit, company's refusal to accept accounting records and inspectors.
It looks the simplest, but it's actually the easiest to write wrong in law.
In particular, joint-stock companies are restricted by company law from buying back their own shares.
Article 167 of the Company LawIn principle, companies are prohibited from arbitrarily reclaiming or buying back their own shares, except in cases where exceptions are provided by law.
Therefore, it is not appropriate to simply state in the shareholder agreement or negotiations: "The company must repurchase the shares whenever a shareholder wants to exit."
Then they assumed that it could be executed directly.
Whether the company itself can acquire the property requires further verification regarding: company type; legal grounds; procedures; financial restrictions; and capital maintenance regulations.
In practice, the real buyer in a "buyout" transaction is often: Another shareholder or third party, Rather than the company itself.
Joint-stock companies are prohibited from arbitrarily buying back their own shares in order to prevent the arbitrary flow of company capital back to shareholders. This affects: company capital; creditors; and other shareholders.
Although the Company Law provides for several exceptions that allow a company to buy back its own shares, each exception has the following: specific reasons; procedures; conditions; and purposes.
For exampleArticle 167 of 1The company's share buyback system has its specific legal purpose and is subject to quantity and amount restrictions. It cannot be interpreted as meaning that every shareholder can ask the company to buy them out using this clause whenever they want to exit.
An exit plan can be designed, but the wording must be very careful.
If the agreement stipulates that another shareholder, founder, specific investor, or a third party bears the obligation to purchase, this is one scenario.
If the requirement is that "the company itself must buy back the shares," then the restrictions under corporate law on a company buying back its own shares must be checked separately.
We cannot ignore mandatory legal provisions simply because the contract states that "the company shall repurchase".
Therefore, the exit clause in the shareholders' agreement should clearly state the buyer.
This is also a typical 50-50 stalemate.
A said, "I built this company from scratch, so I'll buy yours."
B also said, "All the customers are mine, I'll buy from you."
At this point, you can consider designing a negotiation mechanism: mutual quotation; third-party valuation; bidding; phased payments; exchanging different assets; business segmentation.
However, the actual mechanism adopted depends on: whether the company can be divided; whether the brand can be dismantled; whether customers can be transferred; who owns the intellectual property; how employees will be arranged; and the lease agreement and bank financing.
You can't just use an abstract concept like "half for each person" to handle all company assets.
At least the following should also be addressed: Director positions; Changes in responsible persons; Bank authorization; Company seal; Online banking; Company credit cards; Guarantee liabilities; Shareholder loans; Retained earnings; Litigation; Accounting books; Customer information; Intellectual property; Non-competition agreements; Confidentiality; Employees; Past liabilities.
If only the following agreement is signed: "Party A purchases shares of Party B for 5 million yuan."
The remaining issues remain unresolved; although the shareholders have withdrawn, the dispute may not be over.
Many shareholders are also: directors; responsible persons; guarantors of bank loans; joint guarantors of leases; and guarantors of suppliers.
Even if the equity has been transferred, the individual may still be liable for debt risks if the original personal guarantee has not been released.
Therefore, the exit agreement should confirm: which guarantees need to be released; whether the bank agrees to replace the guarantor; and when the original shareholders will no longer be liable.
Withdrawal of equity does not mean that personal guarantees automatically disappear.
Whether a capital increase is permitted depends on: company type; board of directors/shareholders' authority; articles of association; new share issuance procedures; shareholder subscription rights; and resolution procedures.
Capital increases should not be simply regarded as a weapon to resolve shareholder conflicts.
If there are disputes regarding the purpose, procedures, or authority of the capital increase, it may further trigger: board resolutions; shareholders' meetings; new share issuance; and litigation related to management rights.
If a company is preparing to take significant actions that could change control, it should assess as early as possible whether preservation procedures are necessary.
uncertain.
If the following have occurred: a major asset sale; transactions involving unusual related parties; outflow of company funds; transfer of customers, trade secrets, or equipment; preparation for a change of directors; an imminent transfer of shares; or a potential irreversible change in company control, then the case is no longer simply about "disagreements over share price."
The following issues may need to be addressed first: preservation of company assets; shareholder rights; validity of the board of directors/shareholders' meeting; provisional injunction; or other civil proceedings.
Withdrawal from negotiations and emergency preservation measures must sometimes be carried out simultaneously.
If the doubts involveCompany funds misappropriated or related-party transactionsThe specific cash flow and urgent risks should be clarified first before arranging negotiations and court proceedings.
If, in a joint-stock limited company, the board of directors fails to act or is unable to exercise its powers, and this has already caused potential harm to the company, Article 208-1 of the Company LawGiven: interim administrator system.
When the requirements are met, the court may, upon the application of an interested party or the prosecutor, appoint one or more temporary administrators to act on behalf of the chairman and the board of directors.
This is a: Allowing the company to continue operating temporarily Tools.
It does not mean granting a single shareholder permanent operating rights.
No, it's not: a shareholder exit mechanism.
Limited liability companies should also confirm the applicability of their respective company law provisions.
It is important to clearly distinguish between:
Objective: The company must survive.
Problem: The board of directors is no longer able to exercise its powers properly.
Function: To temporarily maintain corporate governance and necessary operations.
Objective: To close the company.
Problem: The company's operations have encountered significant difficulties or suffered substantial damage.
Result: The company proceeded towards dissolution and liquidation.
Therefore: One is: Save the company.
The other one is: The company is closing down.
They cannot be used interchangeably.
Article 208-1 of the Company Law
The board of directors fails to act or is unable to exercise its powers, which could potentially harm the company.
Purpose: To maintain the company's necessary operations. Not for shareholders to withdraw.
The company is experiencing significant difficulties or substantial damage in its operations.
Purpose: To terminate the company and proceed with dissolution/liquidation. Shareholders applying for the closure of a joint-stock company must note: have held shares for at least 6 months and possess a total issued share capital of 10% or more.
A 50-50 deadlock will not automatically lead to the dissolution of a company.
Article 11 of the Company LawProvided: Court-ordered dissolution system.
if: The company's operations are experiencing significant difficulties or substantial damage. Shareholders may apply to the court for a ruling to dissolve the company in accordance with the law.
However: Shareholders arguing does not automatically mean that the company should be dissolved.
The court will consider: whether the deadlock has genuinely affected the company's operations; whether the problem can be resolved through other governance methods; whether the company can still operate normally; the extent of the damage; and the necessity of dissolution.
This should generally be considered a tool for assessment only when corporate deadlock is very serious, not the first step in every shareholder disagreement.
according toArticle 11 of the Company LawA joint-stock company must consist of: Continue for more than 6 months hold: Total issued shares of 10% or more The shareholders filed a petition.
Therefore, when a court-ordered dissolution is involved, the first thing to confirm is: the company type; the shareholding ratio; and the holding period.
Just because "I am a shareholder" does not presuppose that I am eligible to file a petition.
This is very important.
If the court rules to dissolve the company, the legal effect is neither that the court finds a buyer for one of the parties, nor that the other shareholder must buy it out.
Instead, the company is heading towards dissolution and liquidation.
Therefore, if the original real purpose was simply: "I want to leave, but the company is still doing well."
Demanding the company's dissolution directly may not be the most economically beneficial solution.
For example, a company that: has stable revenue; has employees; has customers; has a brand; has technology; and has long-term contracts.
The real problem is simply that the two founders are completely unable to work together.
In this situation: allowing the company to continue operating, but having one person take over, often preserves more value than liquidating the entire company.
Therefore, resolving shareholder deadlock cannot solely rely on the strongest legal weapons.
You should look for: The best solution to preserve the company's and its equity value.
InvolvingEquity investment and investment contract disputesAt that time, the original investment documents and the basis of the claim should still be confirmed;Disputes over company business and management rightsThe company's continued operation and exit from the transaction must be considered simultaneously.
At least organize:
Company Type, Articles of Association, Company Registration
Who holds how much equity and when did the changes occur?
Directors, supervisors, chairman's voting rights
Exit Preferred Purchase and Tractor Sale Valuation
Recent financial reports: bank borrowings, shareholder transactions, retained earnings
Key customer contractual assets brand technology
Bank guarantee lease director's liability and other joint and several liability
Should I stay?
Do I want to quit?
Or do you just want to save the company first?
In many cases, what's truly needed in the end is to first clarify: legal rights; company control; company value; and urgent risks.
Further decisions may include: negotiating a buyout; finding a third-party acquirer; enforcing the shareholders' agreement; initiating a shareholders' meeting or corporate governance proceedings; taking preservation measures; or assessing dissolution if the business truly cannot continue.
Lawsuits are one tool, not the only solution to a stalemate.
Shareholder exit cases typically involve: company law; equity; shareholder agreements; corporate governance; financial information; valuation; civil litigation; and negotiation.
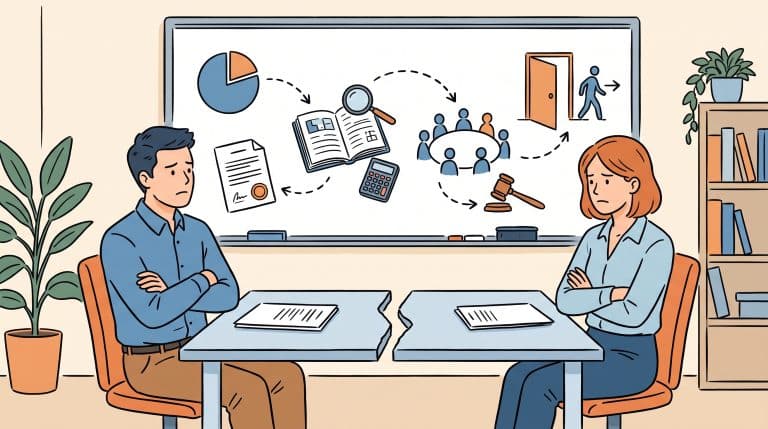
When handling these types of cases, Fidelity Law Firm first creates: a shareholding chart; a governance chart; a financial chart; a liability chart; and an exit strategy.
Further confirmation is needed: Was the deal bought out by other shareholders? Or was it acquired by a third party? Should it be handled according to the shareholders' agreement? Should the accounts be checked first? Should corporate governance be addressed first? Or has the case become so serious that court intervention is required?
Lawyer Li YushengHaving previously served as the legal director of a large accounting firm, when handling corporate and equity cases, I would examine corporate governance, transactions, financial data, and the ultimate business objectives of shareholders simultaneously, rather than simply addressing shareholder conflicts based on a single provision of corporate law.
First, confirm the company type, articles of association, board seats, shareholder agreement, and the true source of the deadlock. Then, assess options such as share buyout, third-party acquisition, shareholder or board meeting procedures, preservation measures, and court proceedings if the company is experiencing severe operational difficulties. A 50-50 situation does not mean there are no legal solutions.
Generally, a shareholder cannot demand the return of their original investment simply because they want to exit. Equity investment and company loans are different legal relationships, and exit usually requires equity transfer, buyout agreement, contractual mechanism, or other legal procedures.
Article 111 of the Company LawThe transfer of equity in a limited liability company is subject to the consent of other shareholders and a system of priority acquisition; the transfer thresholds for general shareholders and directors are also different, and therefore should be handled according to the shareholder's status and specific transaction conditions.
In principle, a general joint-stock company shall...Article 163 of the Company LawShares are freely transferable, but there are still special legal provisions. Closed-end joint-stock companies can stipulate restrictions on share transfers in their articles of association, so the company type and articles of association must be confirmed first.
It cannot be generalized to assume that all shareholders have this right. A joint-stock company's right to buy back its own shares is protected.Article 167 of the Company LawDespite these restrictions, there must still be a legal basis and compliance with relevant procedures. In practice, shareholder buyouts are often handled by other shareholders or third parties.
Not necessarily. Equity value can be influenced by a company's assets, liabilities, profits, cash flow, customers, brand, technology, contracts, and other factors. The initial investment is only the historical cost and does not equal the current equity value.
Article 11 of the Company LawThe regulations stipulate that when a company faces significant difficulties or substantial damage, shareholders may petition the court for its dissolution. For joint-stock companies, shareholders may request an additional period of continued shareholding and a shareholding threshold (10%). The court will ultimately determine the outcome based on the specific deadlock and the company's operating conditions.
If the board of directors fails to act or is unable to exercise its powers, and this puts the company at risk of harm,Article 208-1 of the Company LawThis may involve a temporary administrator system. However, the function of a temporary administrator is to maintain the necessary operation of the company, not to serve as a tool for equity withdrawal or permanent acquisition of management rights.
The guarantee will not automatically disappear due to the transfer of shares. It is still necessary to confirm whether to terminate or replace the guarantor based on the original guarantee agreement and the creditor's consent. Therefore, personal guarantee liabilities must be dealt with simultaneously when withdrawing from negotiations.
If there is an imminent risk of significant asset transfer, change of control, or loss of data, it may be necessary to first assess preservation measures or other court proceedings before simultaneously conducting equity exit negotiations.