Telephone
02-77093611
Line
@fdlaw
address
17th Floor, No. 180, Section 2, Dunhua South Road, Da'an District, Taipei City
Telephone
02-77093611
Line
@fdlaw
address
17th Floor, No. 180, Section 2, Dunhua South Road, Da'an District, Taipei City


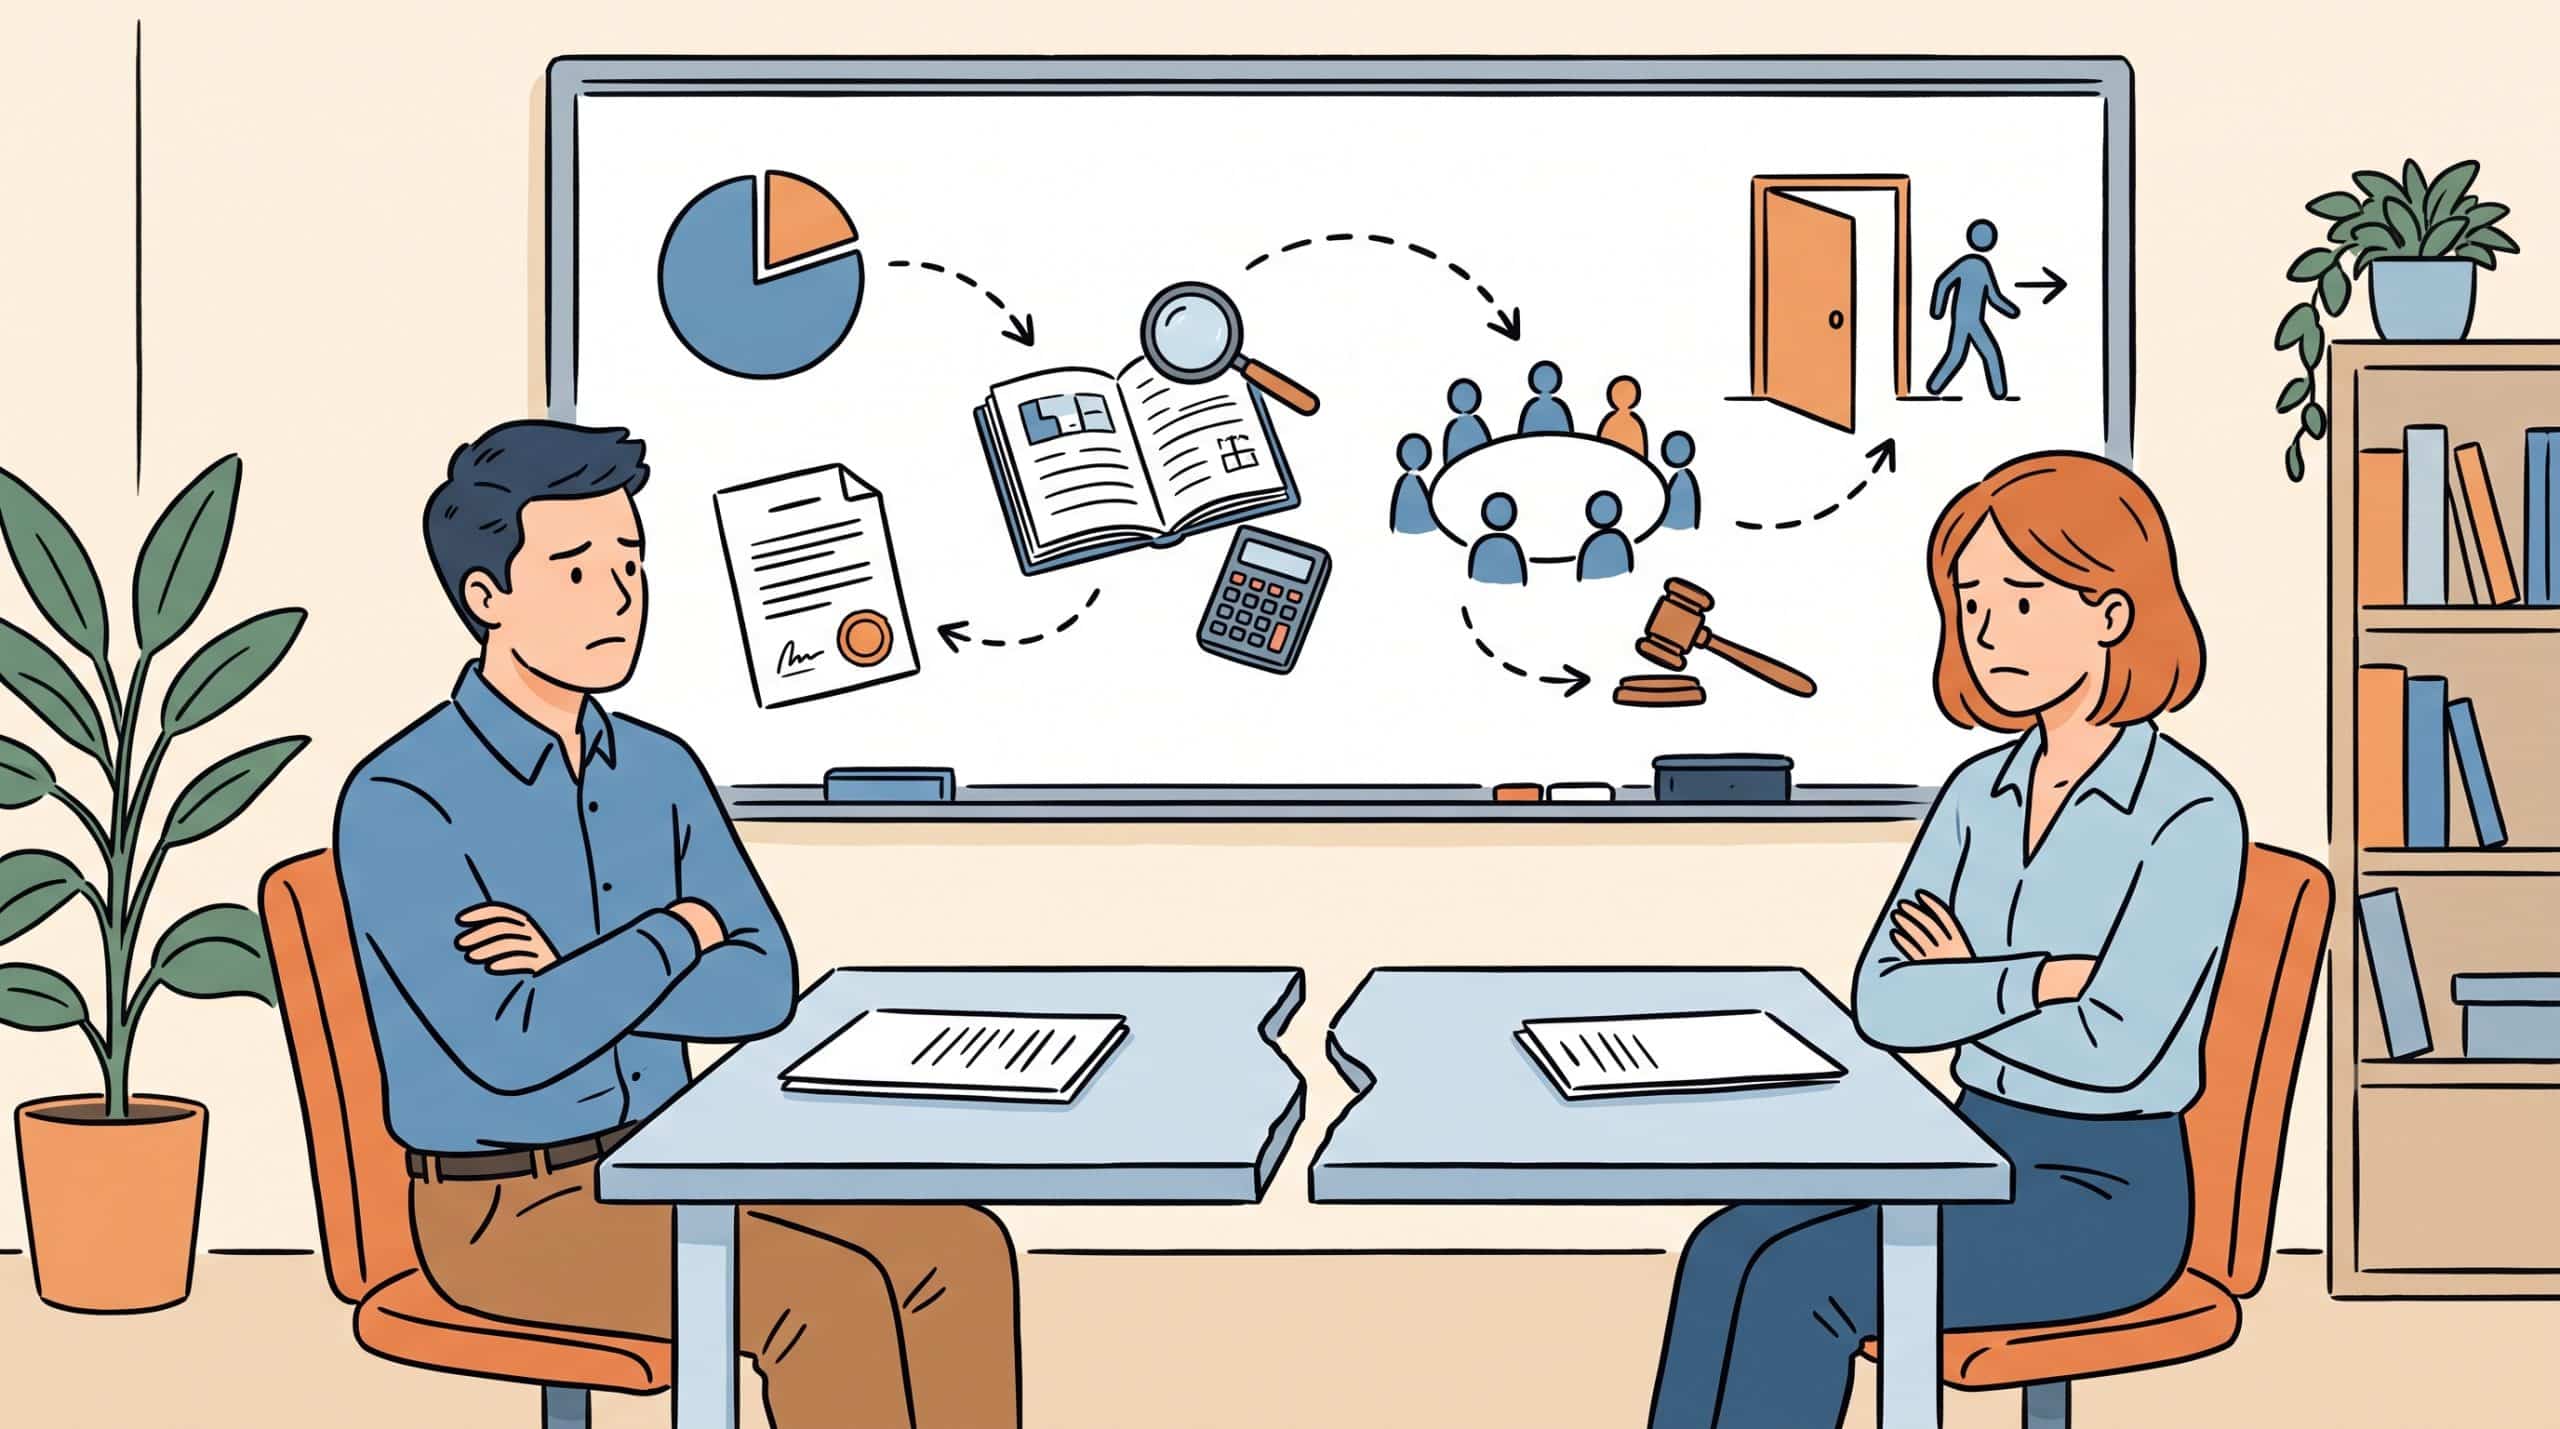
When conflicts arise among company shareholders, the real difficulty often lies not in the differing opinions, but in the fact that the conflict has begun to affect the company's accounts, board of directors, shareholder meetings, seals, bank accounts, important contracts, or business decisions. Appointment is necessary.Lawyers specializing in shareholder disputes and equity controversiesWhen processing, shareholding, board seats, accounting books, and the ultimate target should be provided together to confirm the appropriate procedures.
Common scenarios include: two groups of shareholders each holding nearly half the shares, making it impossible to pass any major decisions; a major shareholder controlling the company but refusing to provide information; shareholders suspecting that company funds have been transferred to related companies; directors losing trust in each other; minority shareholders wanting to audit the accounts but being repeatedly refused; and even one party wanting to leave the company but unable to find a reasonable way to exit their equity.
At this point, the most important thing is usually not to immediately send a strongly worded lawyer's letter, but to first answer four questions:
Is the company a limited liability company, a joint-stock company, or a closed joint-stock company?
What are the actual shareholdings, board seats, and voting rights of each party?
What company books, financial documents, and meeting materials are currently available to you?
Ultimately, what they really want is to regain control of the company, stop certain behaviors, hold those responsible accountable, or leave the company?
Different answers will determine the completely different paths that should be taken, such as auditing, inspecting the person in charge, shareholder meeting, removal of directors, civil litigation, criminal proceedings, equity acquisition, or even company dissolution.
If there are already issues such as obstruction of audits, deadlock at shareholders' meetings or board meetings, suspected transfer of company funds by responsible persons, conflicts of management rights, or equity withdrawal problems, you can first organize the articles of association, shareholding structure, meeting minutes, and a summary of the current disputes.
The real core of shareholder disputes is often not the percentage of shares held, but rather "who currently controls the company."
When handling cases, it is usually necessary to first organize the company registration, articles of association, shareholder register, shareholder agreement, previous capital increases, list of directors and supervisors, board seats, bank account access, custody of official seals, access to financial and accounting systems, and who signed important contracts.
For example, a shareholder holding 45% shares does not necessarily mean they lack substantial influence. If they also control a board seat, the company seal, the financial system, and major clients, their actual negotiating position may be stronger than simply holding 45% shares.
Conversely, even if a company holds more than half of the shares nominally, the outcome cannot be determined solely by looking at the company register if there are other stipulations in the shareholders' agreement, preferred shares, voting rights arrangements, or board composition.
Therefore, the first truly useful document in a shareholder dispute is usually not the complaint, but a complete "shareholding and control structure table".
For handling broader corporate governance, business contracts, and corporate disputes, further reference can be made to Fidelity Law Firm.Business lawyers and corporate legal services.
Many shareholder disputes begin with the question:
"I'm a shareholder, why can't I see all the company's accounts?"
This issue cannot be generalized.
The shareholder rights structure of limited liability companies and joint-stock companies is not entirely the same.
According to the provisions of the Company LawIn principle, shareholders in a limited liability company who do not perform business duties have the right to monitor the company's business and may, in accordance with the law, access specific company information or take necessary measures regarding matters under their supervision.
Therefore, if the company is a limited liability company, the first step should be to confirm whether the shareholder is an executive shareholder, what the company's articles of association stipulate, and what the relationship is between the information requested and the supervisory authority.
Joint-stock companies have a different system.
For example, Article 210 of the Company Law stipulates that a company shall keep its articles of association, minutes of all previous shareholders' meetings, financial statements, and shareholder register, among other documents. Eligible shareholders may, in accordance with the law, request to inspect, copy, or reproduce certain documents.
However, please pay special attention to the following:
"Shareholders are entitled to access certain company information in accordance with the law" does not mean that "any shareholder can demand the company to hand over all accounting vouchers, bank accounts and all transaction documents without restriction".
If a thorough investigation into a specific transaction, related-party cash flow, or company assets is truly necessary, further evaluation is often required to determine whether the conditions for requesting the court to appoint an inspector are met. For details regarding obtaining information and the inspector's procedures, please refer to [link to relevant documentation].When a company does not grant shareholders the right to inspect its accounts, and the procedures for such inspections are as follows:.
For joint-stock companies,Article 245 of the Company LawIt is a very important tool in shareholder disputes.
According to the current Company Law, shareholders who have held 1% or more of the total issued shares for more than six months may apply to the court to appoint an inspector after providing reasons, evidence and explanations of necessity. The court will then inspect the company’s business accounts, financial status, specific matters, specific transaction documents and records to the extent deemed necessary in each case.
This is very different from the usual practice of shareholders demanding "show me the books."
In situations where an inspector-led system is truly suitable, for example:
The company has had revenue for many years, but has consistently claimed that it has no profit.
The ledger shows a large number of related-party transactions;
The company's funds frequently flow to specific shareholders or their related companies;
The person in charge refused to explain certain high payments;
Shareholders have reasonable suspicion that company assets were disposed of at a low price;
There is a significant discrepancy between the financial statements and the actual operating conditions.
However, the court will not allow a full investigation of the company simply because a shareholder says, "I suspect there is a problem."
When filing a complaint, you must still present specific facts and explain why an inspection is necessary, what needs to be inspected, and the relevance of the scope of the inspection to the dispute.
Therefore, in truly effective prosecutorial cases, evidence preparation usually begins before the application is even filed.
If the issue specifically points to misappropriation of company funds, related-party transactions, or company asset stripping, further reference can be made to "Shareholders suspect that the person in charge misappropriated company funds.This is a special topic on the subject. In such cases, information should typically be obtained and the transaction reconstructed before deciding whether to proceed with civil or criminal proceedings.
It is possible, but it must be done in accordance with the shareholding and procedural requirements stipulated in the Company Law.
According to Article 173 of the Companies Act, a shareholder who has held more than 3% of issued shares for more than one year may request the board of directors to convene an extraordinary general meeting of shareholders by submitting a written proposal stating the proposed matters and reasons.
If the board of directors fails to issue a notice of convening within 15 days of the request, eligible shareholders may convene the meeting themselves after obtaining permission from the competent authority in accordance with the law.
in addition,Article 173-1 of the Company LawThere is also a more direct approach:
Shareholders who have held more than half of the total issued shares for more than three months may convene an extraordinary general meeting of shareholders in accordance with this provision.
These two provisions are very important in disputes over operating rights, but they should not be confused.
The procedures for convening a meeting of 3% shareholders and those for shareholders holding more than half of the shares to convene a meeting are different in terms of qualifications and procedures.
Therefore, before deciding to convene a shareholders' meeting on its own, it is necessary to at least confirm the shareholding period, shareholder register, reasons for convening the meeting, meeting notice, agenda items, and subsequent registration procedures for changes.
If the convening procedure of a shareholders' meeting is flawed, even if the voting result is favorable to oneself, disputes may still arise regarding the validity of the resolution.
First, it is necessary to distinguish whether the problem lies in the "convenient procedure or voting method" or "the content of the resolution itself is illegal".
according toArticle 189 of the Company LawIf the convening procedure or resolution method of a shareholders' meeting violates laws or articles of association, shareholders should, in principle, file a lawsuit with the court to revoke the resolution within 30 days from the date of the resolution.
If the content of a shareholders' meeting resolution itself violates laws or articles of association, Article 191 of the Company Law stipulates that the resolution is invalid.
This difference is important.
Because cases that are "revocable" usually involve statutory periods, once these periods are exceeded, relief may be affected.
Therefore, if one party suddenly convenes a shareholders' meeting, elects new directors, changes the person in charge, amends the articles of association, or passes a major asset disposal, it is not advisable to continue the debate within the company after receiving the notice. Instead, one should immediately confirm whether the person with the right to convene the meeting, the notification procedure, the shareholding calculation, the voting rights, and the content of the proposal are legal.
The most direct way is usually through a shareholders' meeting.
Article 199 of the Company Law stipulates that a director may be dismissed at any time by resolution of the shareholders' meeting; however, if a director is dismissed without justifiable reason during his term of office, he/she may claim damages against the company for such damages.
The law also sets special requirements for the attendance and voting thresholds at shareholders' meetings for the removal of directors, so it cannot be handled simply in the same way as a general ordinary resolution.
If the situation is more serious, such as if a director's conduct in the course of business has seriously harmed the company, or if there is a serious violation of the law or articles of association, and the shareholders' meeting has not removed him/her, Article 200 of the Companies Act provides for a judicial removal system.
According to Article 200 of the Companies Act, if a director performs his or her duties in a manner that seriously harms the company, or if he or she commits a serious violation of the law or the articles of association, and the shareholders’ meeting has not resolved to remove him or her, shareholders holding 3% or more of the total issued shares may petition the court for removal within 30 days after the shareholders’ meeting.
Therefore, "I think this director is not doing a good job" and "has reached the point of being removed from office by court judgment" are two completely different things.
If a judicial removal is to be pursued, the specific illegal acts, damages, and shareholder meeting procedures must all be prepared.
This is a very easily confused issue in shareholder disputes.
If the company itself suffers the loss, the right to claim damages generally belongs to the company, and not necessarily to individual shareholders.
For example, when directors sell company assets to related companies they control at unreasonable prices, the company's assets are usually directly reduced.
According to Article 214 of the Company Law, shareholders who have held 1% or more of the total issued shares for more than six months may first submit a written request to the supervisor to file a lawsuit against the directors on behalf of the company. If the supervisor fails to file a lawsuit within 30 days of receiving the request, the shareholders who meet the requirements may file a lawsuit on behalf of the company in accordance with the law.
Therefore, in shareholder disputes, it is essential to first clarify the following:
Is it the shareholder who suffers the loss, or the company?
This will directly affect who the plaintiff is, what the claims are, and the legal basis.
If the dispute has already entered into litigation, further reference can be made.Corporate commercial litigation and business disputesThe handling method.
uncertain.
This is another common misconception in corporate deadlock cases.
Many shareholders believe that:
"If I don't want to continue, the other shareholder should buy back my shares."
However, company law does not have a general rule that applies to all shareholder disputes, allowing shareholders to force other shareholders or companies to buy back all their shares at a price they desire simply because they "do not want to cooperate anymore".
Whether or not one can actually withdraw usually depends on:
Company type;
Articles of Association;
Shareholders Agreement;
Is there a pre-agreed buyback or exit mechanism?
Right of first refusal;
Valuation formula;
The right to buy or sell under specific default circumstances;
And whether the two parties can reach an agreement on the transfer of equity.
The equity or capital contribution transfer systems of joint-stock limited companies and limited liability companies are not entirely the same.
For example, Article 111 of the Company Law stipulates other relevant restrictions and procedures for the transfer of capital contributions by shareholders of a limited liability company. The rules for the transfer of shares of a joint-stock company cannot be directly applied to a limited liability company.
Therefore, "exiting a company" is not as simple as just saying "I want to withdraw my shares," but is usually a transaction involving legal, financial, and valuation issues simultaneously. For specific exit and transaction arrangements, please refer to [link/reference needed].How to exit, buy out, or dissolve a company in a 50-50 shareholder deadlock?.
In cases involving disputes over original investment, investment agreements, or equity acquisition, you can refer to [the relevant source].Equity investment disputesRelated analysis.
Assuming both parties eventually agree to break up the partnership, the next most common sticking point is price.
One side might say:
"The company makes a lot of money every year, and my 30% is worth at least 30 million yuan."
The other party might think:
"The company mainly relies on my clients and management capabilities; without me, the company wouldn't be worth this price at all."
In practice, equity prices may involve:
Company net worth;
Past revenue and profits;
Undistributed surplus;
Accounts receivable;
Liabilities and potential liabilities;
Do major customers depend on specific shareholders?
Intangible assets such as trademarks, technologies, and customer lists;
Does the equity constitute control?
And whether the company is currently facing significant litigation or tax risks.
Therefore, a good shareholder exit plan is not just about writing "A buys B's shares for a certain amount of money".
Other issues to be addressed include payments, closing, director resignations, seals and bank authorizations, company document handover, guarantees, shareholder loans, non-competition agreements, confidentiality, and subsequent claims.
While company law does include a court-ordered dissolution system, this should be considered a back-end processing tool, rather than something to be used every time a shareholder conflict arises.
according toArticle 11 of the Company LawWhen a company faces significant difficulties or suffers substantial damage in its operations, the court may, under statutory conditions, order its dissolution upon the request of its shareholders.
For joint-stock limited companies, Article 11 of the Company Law further requires that the claiming shareholder must have held more than 10% of the total issued shares for more than 6 months.
The situations that truly require consideration of court-ordered dissolution are usually not simply cases where "everyone is arguing."
The likely scenario is that corporate governance has been completely dysfunctional for a long time, key decisions cannot be made, operations are substantially affected, and other milder approaches have failed to resolve the issue.
Once a court-ordered dissolution is successful, the direction is to end the company's legal existence and enter into liquidation. Therefore, it is necessary to first assess its consequences for employees, customers, contracts, assets, taxes, and shareholders themselves.
Not every shareholder dispute involves a crime.
Differences in business philosophy, company losses, investment failures, or even a company making a deal that appears to be bad in hindsight, cannot be directly equated with breach of trust, embezzlement, or fraud.
However, if the data shows:
Company funds were diverted for the personal use of the person in charge;
Fictitious transactions were used to transfer company funds to related parties;
Company assets were transferred at a significantly low price;
Creating false documents to conceal the flow of funds;
Intentionally concealing important transactions;
Or, if the person in charge violates their duties and causes damage to company property,
This necessitates a further assessment of whether civil liability under corporate law and criminal liability coexist.
If the issue specifically involves abnormal company funds, related-party transactions, or suspected embezzlement, you can further read the special feature "Shareholders Suspect Executives of Misappropriating Company Funds".
The most important thing in these types of cases is to first rebuild the accounts and cash flow, rather than replacing evidence analysis with a criminal charge.
If shareholders begin to distrust each other, evidence often disappears quickly as the company's authority changes.
In practice, the following should be prioritized for organization:
Articles of Association and their amendments;
Shareholder register and proof of capital contribution or shareholding;
Shareholder agreements and investment contracts;
Notices and minutes of all previous shareholders' meetings and board meetings;
Financial statements;
Legally obtained accounting and transaction records;
Company bank transaction records;
Financial transactions between the company and its shareholders, directors, and related companies;
Important emails, LINE messages, or other communication records;
Who currently controls the company's official seals, online banking, accounting system, and key accounts?
And the equity sale or exit plans that both parties have previously proposed.
However, it should be noted that shareholders cannot illegally obtain company computers, passwords, or other information simply because of a dispute.
Evidence preservation itself must also be legal.
Even though they are both called "shareholder disputes," the purposes of different parties may be completely different.
Some people want to continue running the company, but they just want to replace another director.
Some people don't care about the management rights; they just want to know where the money went.
Some people have discovered that the company appears to have been emptied of its coffers and hope that those responsible will be held accountable.
Some people just want to get a reasonable price and leave the company.
Some people also hope to buy the other party's shares to completely end the co-governance between the two factions.
Therefore, the truly effective strategy is not to throw out all the audits, personnel inspections, criminal charges, and board removals at once, but to first decide what outcome you ultimately want, and then work backward to determine what procedures are needed.
For corporate shareholders, litigation is sometimes a necessary tool, but not necessarily the ultimate goal.
The real purpose may be to obtain information, restore governance, stop asset loss, regain control, or complete the equity exit under reasonable conditions.
If a company wishes to establish fixed contracts, corporate governance, and risk management mechanisms before disputes arise, it can also refer to...Company Law.
Don't just reply to the other person's text.
The first step should be to confirm immediately:
The company's current registration and actual shareholding;
Does the person convening the shareholders' meeting have the right to convene it?
Is the shareholder meeting notice legal?
Can controversial proposals be submitted in accordance with the law?
How are the voting rights of shareholders and directors calculated?
Does it involve a period of suspension of property transfer?
Has the registration of the change been changed?
And whether there is a 30-day relief period.
Especially when there is an illegality in the procedure for convening a shareholders' meeting, the revocation lawsuit under Article 189 of the Company Law involves a 30-day period, and not all the time can be spent on negotiations between the two parties.
It cannot be generalized. First, it's necessary to confirm whether the company is a limited liability company or a joint-stock company, the shareholders' identities, the types of information requested, and their relevant legal rights. General access to information by joint-stock companies and court-appointed inspectors are different levels of the system. While shareholders have the right to information under the law, this does not mean they can obtain all of the company's accounts, banking, and transaction documents without restriction.
No. According to Article 245 of the Company Law, shareholders of a joint-stock company must, in principle, continue to hold at least 1% of the total issued shares for more than six months and provide specific reasons, evidence, and an explanation of the necessity of the inspection before they can apply to the court to appoint an inspector. The court will still review the matters and scope of the inspection; therefore, holding 1% of shares does not necessarily mean that a comprehensive inspection of the company is possible.
In a joint-stock limited company, shareholders who have held more than half of the total issued shares for more than three consecutive months may convene an extraordinary shareholders' meeting on their own if they meet the requirements of Article 173-1 of the Company Law. However, they must still complete the legal procedures for convening, notifying, proposing resolutions, and holding the meeting; holding more than half of the shares does not mean that the procedures of the Company Law can be ignored.
It's necessary to examine the legality of the shareholders' meeting's convening procedures, resolution methods, and removal resolutions, and to distinguish between the rights of the director and the rights of the shareholders. If a director is removed without just cause during their term, issues of damages to the company may also arise. If the convening procedures or resolution methods are illegal, the statutory remedies under company law must also be considered.
In principle, there is no "forced withdrawal" system applicable to all shareholder disputes. Whether withdrawal is possible depends on the company type, articles of association, shareholder agreement, legally stipulated special circumstances, and whether it can be completed through share sale or other transaction arrangements. If both parties decide to dissolve the partnership, further issues such as share valuation, payment, closing, director resignation, shareholder loans, and subsequent liabilities need to be addressed.
If a shareholder deadlock has caused significant difficulties or substantial damage to the company's operations, the court-ordered dissolution system under Article 11 of the Company Law can be further assessed. However, court dissolution is a relatively late-stage measure; it is not necessarily possible to dissolve a company simply because 50/50 shareholders disagree. Relevant legal requirements must still be met, and it must be proven that the company has indeed reached a level of significant difficulties or substantial damage.
Shareholder disputes that remain at the emotional level usually escalate the longer they drag on.
What really needs to be addressed is:
Who controls the company now?
Is the information complete?
Are the company's assets still safe?
Which resolutions may have immediate legal effect?
Does the need for an audit or court inspection apply?
Is there still room for a reorganization of the management rights?
And ultimately, whether to continue operating jointly, have one party buy the other's shares, or end the cooperation.
When handling corporate governance, shareholder disputes, commercial litigation, and corporate criminal cases, Fidelity Law Firm first reconstructs the facts from the company's articles of association, shareholding, meeting procedures, accounting and transaction records, and then decides whether a shareholders' meeting, inspector, preliminary injunction, civil litigation, criminal proceedings, or shareholding negotiations are needed, rather than using all means at once from the outset.
If the company is currently experiencing shareholder conflicts, obstructed audits, disputes over management rights, or equity withdrawal issues, please provide the company registration, articles of association, shareholding structure, important meeting minutes, and a summary of the current disputes. Then, we can determine whether the most pressing issues to address are information, control, accountability, or an exit plan.
If a company has encountered problems such as obstruction of audits, deadlock at shareholders' meetings or board meetings, disputes over management rights, suspected abnormal funds, or equity withdrawal issues, it can first organize the company registration, articles of association, shareholding structure, meeting minutes, and a summary of the current disputes, and then determine which issues should be prioritized: information, control, accountability, or exit plan.