Telephone
02-77093611
Line
@fdlaw
address
17th Floor, No. 180, Section 2, Dunhua South Road, Da'an District, Taipei City
Telephone
02-77093611
Line
@fdlaw
address
17th Floor, No. 180, Section 2, Dunhua South Road, Da'an District, Taipei City


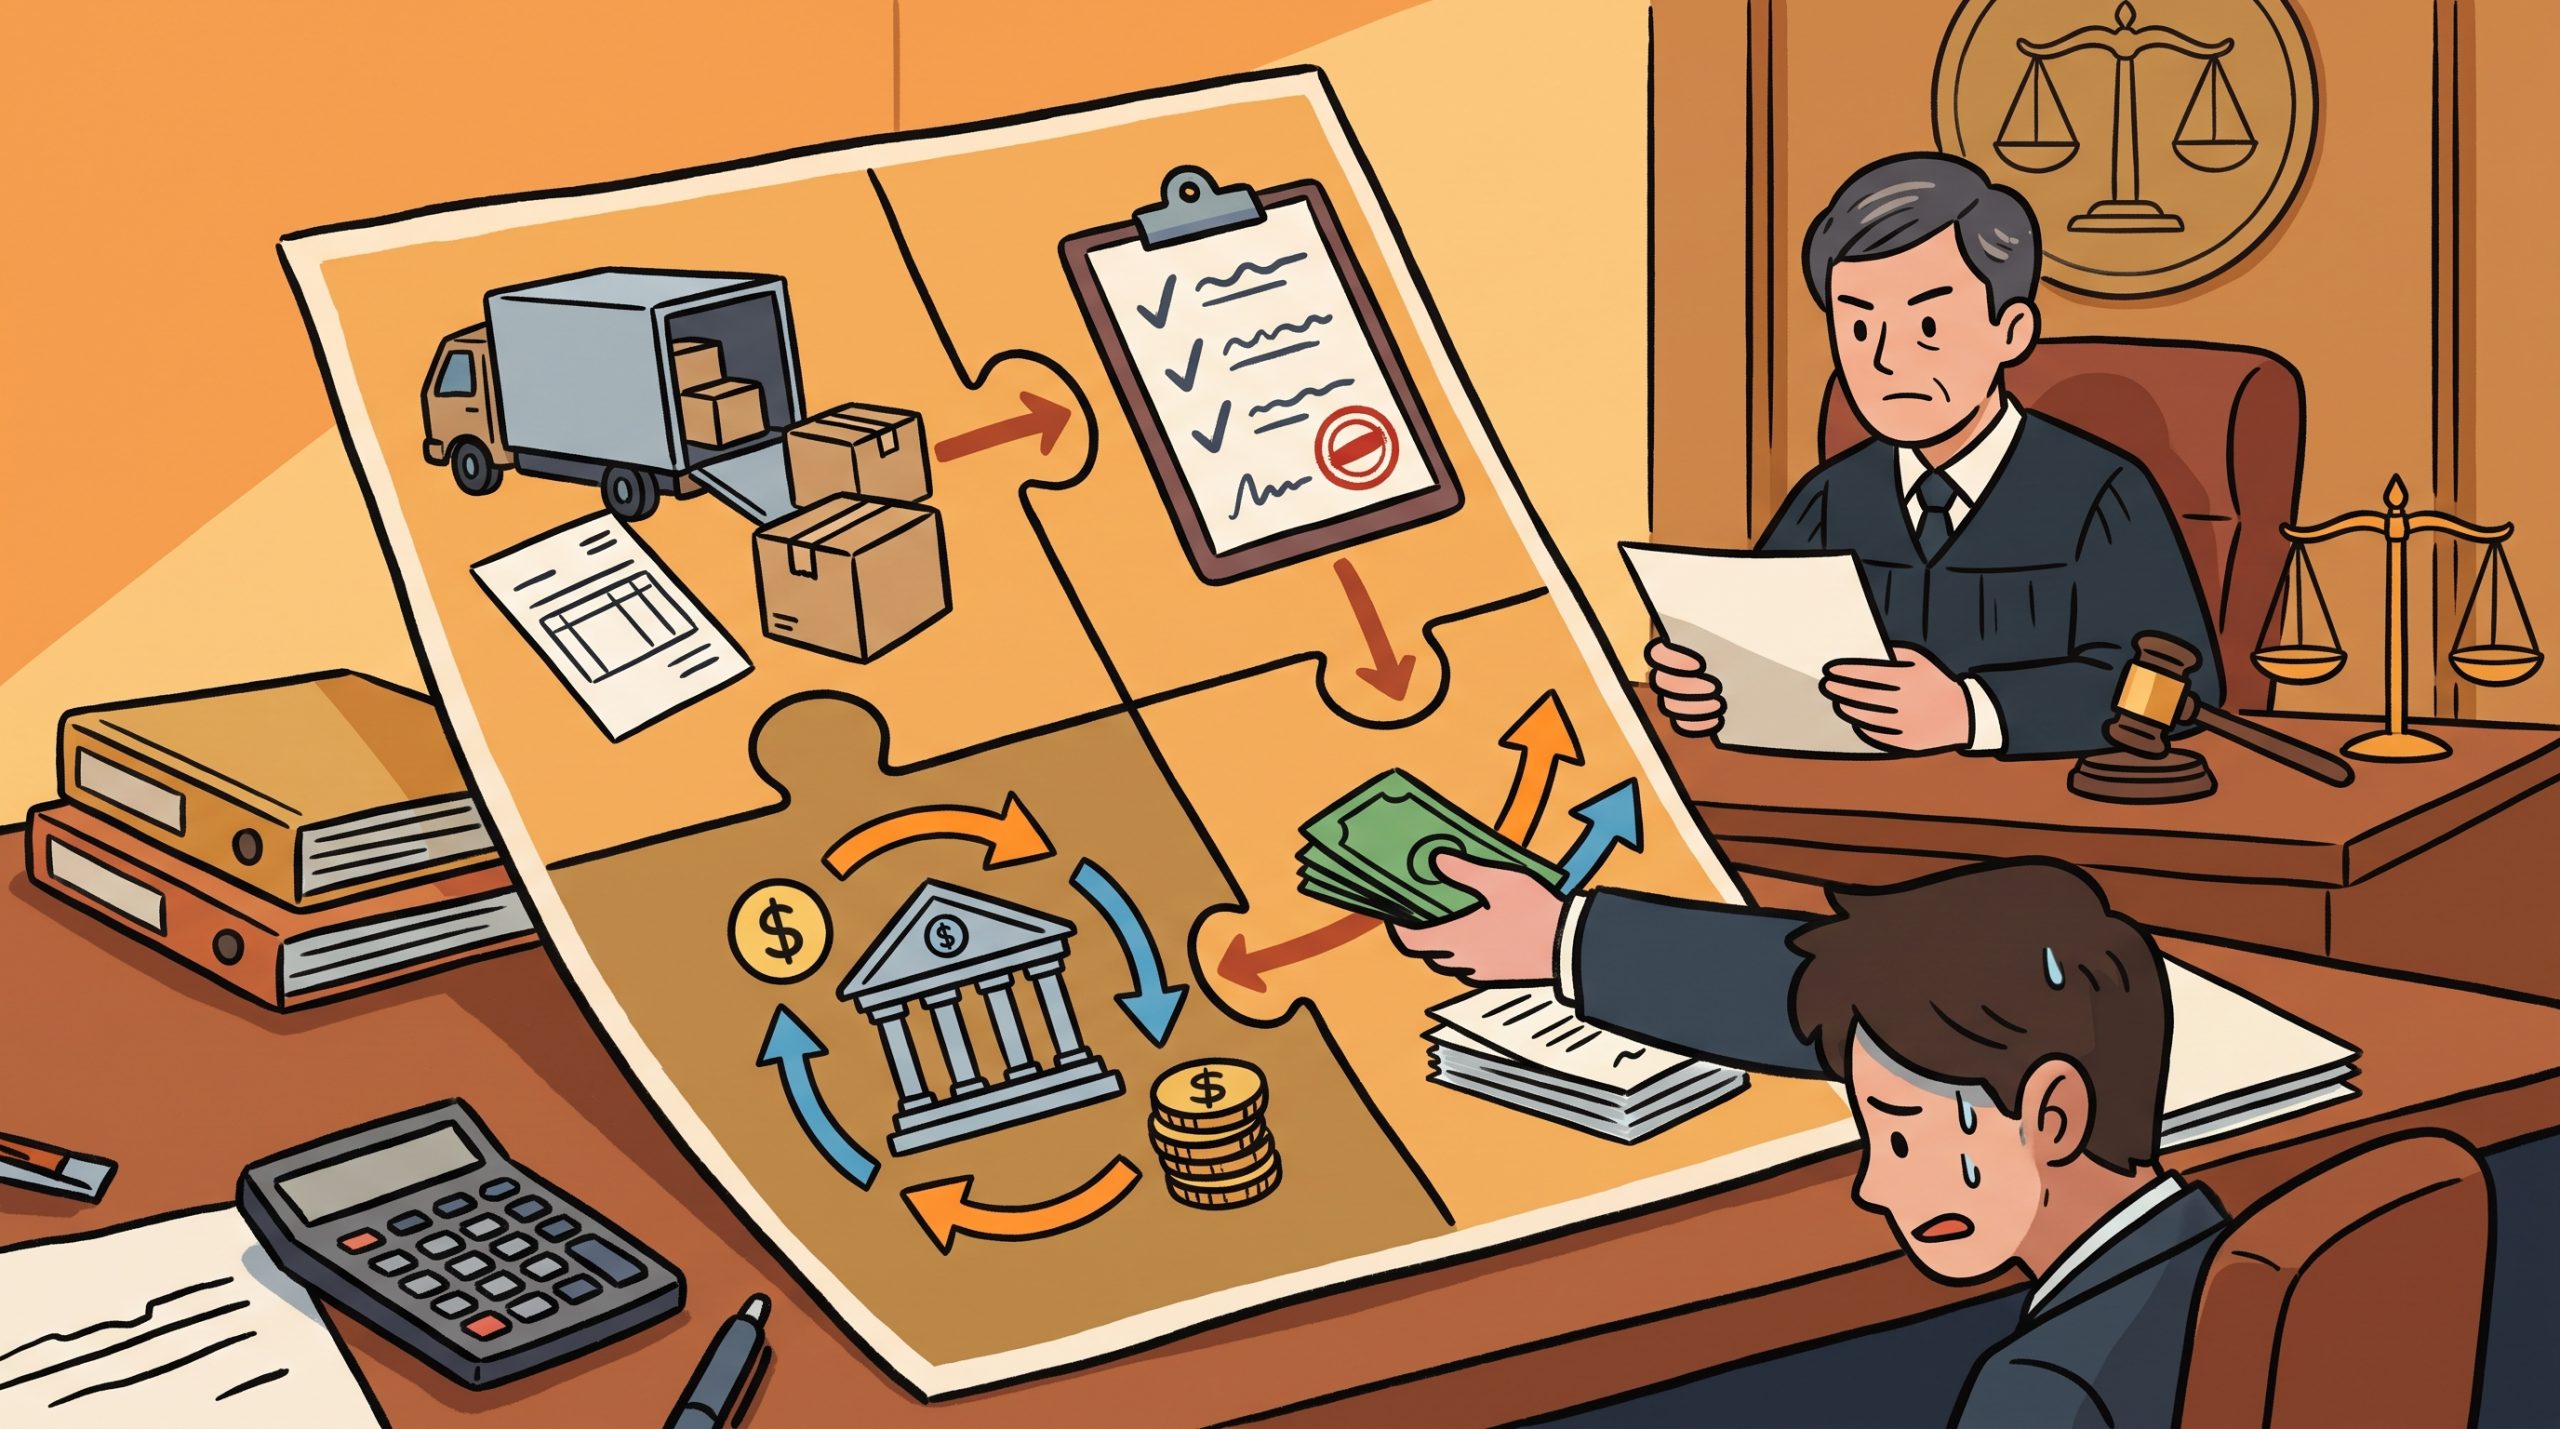
Financial accountants are summoned for questioning and must answer five questions first:
1. What exactly are my official job title and my actual work?
2. Do I only know about transactions and funds, or do I only know about accounting documents?
3. Who provided the materials involved in the case, and who decided on the method of recording them in the accounts?
4. Have I ever requested additional information, objected, or raised any corrections?
5. Did I sign the financial statements, and did I actually participate in the alleged false statements?
When a company is involved in cases of financial misrepresentation, fraudulent transactions, or commercial accounting law violations, the people most frequently implicated in criminal proceedings, besides the chairman and general manager, are:
Chief Financial Officer;
Finance Manager;
Accounting supervisor;
Chief Accountant;
The accounting personnel in charge;
And those who actually operate the ERP system or prepare accounting vouchers.
When these individuals are interviewed by the investigation bureau, they often present two completely contradictory ideas.
The first type is:
"I was just doing the bookkeeping as instructed by the boss. I didn't make the decisions, so it shouldn't have anything to do with me."
The second type is:
"I entered the data into the accounts and signed the financial statements, so does that mean I'm guilty just because the company has problems?"
Both of these interpretations are oversimplifications.
The real questions that need to be asked in major financial statement criminal cases are:
Who decides on the deal?
Does anyone know the original transaction details?
Who provides the accounting information?
Who decides how the money is deposited?
Who actually inputs or prepares the accounting data?
Who will review it?
Who signed it?
Has anyone expressed opposition or demanded a correction?
Criminal liability is not automatically established simply because one works in the finance department.
However, "I was asked to do it by my supervisor" does not automatically absolve me of responsibility.
What the CFO, accounting supervisor, and accounting staff really need to deal with is their own performance throughout the entire process:
Transaction → Voucher → Posting → Financial Statement → Announcement
The actual location within the process. See related topics for further information.Defense against listed companies for false financial statements, fraudulent transactions, and commercial accounting laws.
The most common mistake in major financial reporting cases is treating all financial accountants as the same group of people.
This may actually include:
Chief Financial Officer;
Finance Manager;
Accounting supervisor;
Chief Accountant;
Accountant in charge;
Cashier;
Tax officials;
ERP input personnel;
General administrative staff.
Each person's:
Legal status;
Company position;
Decision-making power;
Information scope;
and actual behavior
They may all be different.
Therefore, it cannot be solely because:
"He's in the finance department."
This leads to the conclusion that he knew all the fake transactions.
It is also not because:
"He is not a board member."
He believed that the criminal liability for major financial statements was definitely not his concern.
Financial/funding decisions, actual responsibilities vary from company to company.
Accounting review / financial statements / may involve statutory signatures
Judgment based on the actual company accounting organization
Actual voucher, voucher, and accounting work
Article 36 of the Securities Exchange LawThere are clear requirements for the signatures and seals on financial reports that are required to be published or declared in accordance with the law.
The annual financial reports of publicly traded companies are subject to the following legal requirements:
Chairman;
Manager;
Accounting supervisor
Signature or seal.
The financial reports for the first, second, and third quarters also have corresponding signing and sealing requirements.
therefore:
The accounting supervisor is not only responsible for bookkeeping within the company.
In the financial reporting system of publicly listed companies, he may also be a person who is legally required to sign and seal the financial reports.
This is why accounting supervisors often become key targets of investigations in major financial reporting cases involving listed companies.
This is what many people only pay attention to.Article 171Financial reports are not up-to-date, making them an easily overlooked regulation.
Article 174, Paragraph 1, Subparagraph 6 of the Securities Exchange Act stipulates:
Managers or accounting supervisors who sign off on relevant financial reports may face consequences if the financial reports contain false information:
Imprisonment for a term of not less than one year but not more than seven years
He was also fined.
Therefore, for publicly listed companies:
The financial report contained inaccurate information;
Financial statement signing;
Actual accounting treatment
This could simultaneously lead to different criminal legal issues.
Don't just look atArticle 71 of the Commercial Accounting Act.
We cannot rely solely on Article 171 of the Securities Exchange Act.
This firm has a separate office.Major financial criminal cases and criminal defense in financial accountingA dedicated service page that integrates defense efforts related to searches, detention, transaction flows, and accounting documents.
Fidelity Law Firm has recently been engaged again to handle a major securities transaction law criminal case involving multiple defendants, investigative detention, and a large amount of corporate, financial, transaction, and criminal evidence. Attorney Li Yusheng is involved in reviewing the case files and providing criminal defense. Due to the confidentiality of investigative proceedings and the interests of the clients, the firm will not disclose the case number, names, or undisclosed details, nor does this indicate that the recent case involves any specific financial accounting crimes described herein.
Attorney Li Yusheng previously served as the legal director of a large accounting firm. When handling financial statements, commercial accounting, and major financial criminal cases, he would make a special distinction between the information scope, decision-making authority, and actual actions of directors, chief financial officers, accounting supervisors, chief accountants, and actual personnel.
The same company and the same financial report do not mean that every defendant bears the same criminal responsibility.
Related cases can be handled byCorporate Criminal and White-Collar Criminal LawyersIntegration and processing.
If your company has been searched, or if you have been questioned for making false financial statements, engaging in fraudulent transactions, inflating revenue, using false vouchers, or making accounting entries, you should first compile a list of your job responsibilities, approval authority, the transactions involved, ERP and email records, and whether you raised any objections at the time, and then confirm which criminal liability you are facing.
You can't draw conclusions just by looking at the English title "CFO".
The actual organization of the company may differ.
Some companies' CFOs are also:
Finance Manager;
Manager;
He even served as the accounting supervisor.
Some companies, on the other hand, consider:
finance;
Accounting
They are divided into different departments, each headed by a different supervisor.
Therefore, the first thing to confirm in a criminal case is:
The company is formally organized;
Registration;
Internal responsibilities;
Financial statement signing;
Board of Directors Information;
And the actual work content.
Professional title is a starting point, not the end point of legal responsibility.
The objects explicitly listed in Section 71 of the Business Accounting Act include:
Business Manager;
Chief accountant;
The accounting personnel in charge;
And personnel who are legally entrusted to handle accounting matters on behalf of others.
If these people:
Knowing that the information is false, they still fill out accounting vouchers or record it in the books;
Intentionally causing the loss or damage of accounting vouchers, ledgers, or statements that should be preserved;
Forging or altering relevant accounting documents;
Intentionally omitting accounting items that should be recorded, resulting in inaccurate financial statements;
Or through other improper means, to produce inaccurate results in accounting matters or financial statements.
It may involve criminal liability.
The current statutory penalty is:
Imprisonment for up to five years, detention, or a fine, or both.
Therefore, the Business Accounting Act is not simply about punishment:
"The person who made the mistake in the accounting."
What the law truly deals with is:
Known and intentional misconduct in accounting.
You can't make that judgment directly.
First, it is still necessary to confirm the CFO's actual legal and professional status within the company.
If the CFO is:
Chief accountant;
Accounting supervisor;
Manager;
Or those who actually instruct or participate in false accounting treatment,
Criminal risk certainly cannot be used in isolation:
"I did not install the ERP system myself."
exclude.
On the other hand, if a CFO:
Not responsible for accounting;
Not involved in the transactions in question;
No accounting treatment has been decided;
I haven't actually had access to the relevant materials.
The prosecution must then present individual pieces of evidence to prove why he bears criminal responsibility.
so:
Whether or not someone personally entered the data is not the only criterion.
What truly matters is the level of actual participation and subjective perception. Related topics can be found in [reference needed].Legal violations and evidence assessment in commercial accounting law.
For example, the accounting supervisor tells the handling accountant:
"This pre-recognized revenue."
or:
"Issue the invoices first, and record them at the end of the year."
If the personnel handling the transaction are simply following normal procedures and have no reason to doubt the transaction itself, then...
and:
Knowing full well that there were no shipments, no customers, and no transactions, they still cooperated in preparing false accounting documents.
Legal evaluations may be completely different.
so:
Supervisor's instructions
It is not an automatic exemption from liability.
Criminal cases will still ask:
What did you know at the time?
Does the file look normal?
Are there any obvious abnormalities?
Have you raised any questions?
How should the supervisor respond?
What did you do after that?
The accounting staff often only receive:
Order;
bill;
Acceptance form;
Shipping documents;
Supervisor's approval
Then the accounting is processed.
If the front-end business or management deliberately creates complete formal documents...
But accountants did not:
Contacting customers;
Contact with goods;
Controlling cash flow;
Participate in transaction design;
There is no other evidence to suggest that he knew the transaction was fraudulent.
Not just because:
"He entered the ERP records."
This directly leads to the conclusion that the perpetrator possessed full criminal intent.
Therefore, what criminal defense truly needs is:
Information scope analysis.For related topics, please refer toDefenses against fake transactions, circular transactions, and inflated revenue.
The information can be divided into several layers:
First layer:
Is the transaction real?
Second layer:
Has any shipment been made or any services been provided?
Third layer:
Where does the payment funding come from?
Fourth layer:
How do accountants recognize entries?
Fifth floor:
How will the final financial statements be presented?
Different people may only know one layer.
For example:
Business knows customers;
The warehouse knows when to ship;
The finance department knows when to make the payment;
The accountant knows to record the transaction;
The accounting supervisor knows the financial statements;
The chairman is aware of the major operating results.
It cannot be just because these people are ultimately related to the same financial report.
This leads to the conclusion that everyone knows all the facts.
Nowadays, almost all companies process accounting data electronically.
Article 72 of the Commercial Accounting Act provides for separate provisions regarding electronic accounting data.
For example, intentionally:
Enter false information;
Altering documents;
Delete data;
Items that should be logged in have been omitted;
Or by using other improper means to create false financial statements,
All of these could potentially lead to criminal issues.
Therefore, during searches in major financial cases, prosecutors and investigators typically do not only seize:
Paper-based account books.
Other possible outcomes:
ERP;
System Log;
Account permissions;
Electronic voucher;
Edit records;
Excel;
Email;
Server.
These materials can sometimes clearly show:
Who did what, when, and who?
Suppose we are summoned for questioning three years later, and no one remembers it:
Who altered a summons?
If the ERP is still saved:
account number;
Enter the time;
Modified time;
Approval process;
Version history,
It may be more objective than human memory.
However, it is also important to note:
Account user
Not always equal:
The person actually doing the work.
For example, does the company exist?
Shared account;
Login on behalf of someone else;
Delegation of authority;
System batch processing.
Therefore, electronic records still need to be judged in conjunction with the company's actual work processes.
Article 73 of the Commercial Accounting ActThere are direct regulations on this issue.
If the presiding or handling accountant, or any person involved in processing accounting data electronically, is involved in a crime under Articles 71 or 72,
But beforehand:
He had previously expressed his refusal;
Or suggest corrections;
Moreover, there is solid evidence.
The law stipulates:
They may have their sentence reduced or waived.
So an email that existed at the time:
"There is no acceptance documentation for this transaction, so we do not recommend accepting it."
It might be far more than what was said afterward:
"I objected at the time."
It is more valuable.
For example:
Email;
Approval comments;
ERP Notes;
Company communication software;
LINE work groups;
Meeting minutes;
Internal Memo;
Accountant contacts;
Financial Report Close Meeting Minutes.
For example:
"No acceptance certificate available, please do not enter the transaction into the accounts."
"This transaction should be listed as a related party."
"There is a problem with the timing of revenue recognition."
"I suggest reversing the decision."
"Please have your supervisor confirm this in writing."
All of these may have significant evidentiary value.
But the core remains:
It must be an original record that existed at the time.
This should not be done.
If the company has already been searched or an investigation has begun, and the product is then created:
Emails with reversed dates;
Supplementary comments;
Falsifying past dissent records,
Not only can it not effectively protect itself,
On the contrary, it may produce:
Forgery;
Alteration;
Destroy evidence;
Even collusion
New risks.
What you should really do after the search is:
Preserve existing data;
Do not modify the file;
Do not delete;
Do not ask colleagues to help you supplement documents.
If you require a detailed explanation, you can specify the steps:
Post-hoc explanation of the current date.
It cannot be disguised as a past document.
There is another very important regulation regarding the financial statements of publicly traded companies.
Article 174, Paragraph 1, Subparagraph 6 of the Securities Exchange Act stipulates criminal liability for managers or accounting supervisors who sign and seal financial reports and make false entries in the financial reports.
However, the same policy also stipulates:
If in:
Others reported it;
competent authority;
or judicial authorities
Before conducting the investigation,
Corrections have been proposed.
And provide evidence to report to the competent authority.
The law stipulates:
Reduce or exempt their punishment
According to the regulations.
This is not entirely the same system as Section 73 of the Business Accounting Act.
The applicable objects, requirements, and procedures must be judged separately.
In criminal cases, it's not enough to just say:
"I later considered fixing it."
What really needs to be checked:
When was the problem discovered?
When was it proposed?
To whom should we raise this issue?
Was this before the investigation began?
Did you leave any evidence?
Did they actually report it to the competent authority?
so:
Verbally expressing disagreement;
The company internally requested modifications;
A formal request for correction has been submitted to the competent authority.
It may have different legal implications.
It cannot all be combined into one sentence:
"I object."
It's not that simple.
Financial statement signatures are, of course, very important criminal evidence.
However, confirmation is still needed:
Which part of the financial statement is inaccurate?
Did the accounting supervisor participate in this part of the process?
What information did he obtain?
Are you aware that there is a problem with the information?
Have adjustments been requested?
Whether false front-end information was provided;
Is there any other evidence to prove subjective perception?
Criminal liability still requires proof of the individual's crime.
However, for the accounting supervisor who is legally required to sign and seal the financial reports,
Simply put:
"I'm just signing off on a formality."
It is usually not a complete defense.
That's not how it should be understood either.
Article 174, Paragraph 1, Subparagraph 6 contains specific requirements regarding signatures and seals.
However, major financial reporting cases may also involve:
Article 20 of the Securities Exchange Law;
Article 171;
Other acts under Article 174;
Commercial Accounting Law;
And issues such as principal offenders, co-principals, instigators or accomplices in criminal law.
so:
No signature
This could be an important fact.
However, they cannot be directly equated:
There is absolutely no possibility of any criminal liability.
We still need to observe actual behavior. For related topics, please refer to [link/reference needed].Serious Crimes and Criminal Defense under Securities Trading Law.
It cannot be simplified in this way.
In addition to the status stipulated by special laws, criminal cases
It may also depend onRules of Criminal Law regarding joint principals, instigators, accomplices, and accomplices of crimes committed under the criminal law.judge.
Therefore, no:
Chairman;
Manager;
Accounting supervisor
Official status
This does not mean that if someone actually knows about and actively participates in a crime, they will necessarily be completely free of criminal responsibility.
but:
How much do you know, how much do you participate?
It still needs to be proven.
Working at the same company does not automatically make someone an accomplice. See related articles for further information.The company's head was sued under the Commercial Accounting Law..
Commonly included:
How should the company's funds be allocated?
Why was this payment made in this way?
Where do customers get their payments?
Are you aware of related-party transactions?
Will you participate in the financing?
Will you participate in financial forecasting?
Have you noticed any anomalies in the financial statements?
Did the chairman or general manager give any instructions?
How should the finance department and the accounting department divide their responsibilities?
How should significant accounts receivable be handled?
Therefore, the CFO should confirm the following before scheduling a meeting:
What I am actually responsible for is:
funds;
finance;
Accounting;
Investor relations;
It is still part of it.
Don't assume that the entire work of the finance department is your answer. Confirmation should also be made before the meeting.Investigation and Procedural Defense When Accounting Personnel are Involved in Securities Exchange Act.
Possible includes:
Who decides on income recognition?
Who will review the subpoena?
Which transaction is unusual?
Are any additional documents required?
Why are they still being recognized at the end of the year?
Have you reported this to the chairman, general manager, or chief financial officer?
What did the accountant ask?
How is a financial report closed?
Who ultimately decides not to make any adjustments?
Therefore, the criminal defense of accounting supervisors often relies heavily on:
The working papers and communication records from that time.
For example, the investigator asked:
How do you know this deal is real?
Accountants are only responsible for entering entries into the books.
But in order to cooperate with the answer, he said:
"Because we did ship some goods."
If he had no contact with the shipping process at all
This kind of answer might actually lead the prosecution to believe that:
He knows more.
Therefore, a precise distinction should be made:
I know this myself;
I know this from the documents;
My supervisor told me;
And things I don't know.
Don't guess the answers for other departments.
Not everything can be answered:
"have no idea."
Rather, it pertains to facts that exceed the scope of one's actual job duties and information.
Clearly explain:
Why don't I know?
For example:
"My job is simply to record transactions based on approved documents. I don't have client contact and I'm not responsible for shipping."
This is similar to simplicity:
"I have no idea."
Completely different.
What is truly convincing is:
Job title + process + evidence
It can support the rationale for not knowing.
Can be organized:
business
→ Establish a transaction
Warehouse/Operations
→ Shipment fulfillment
finance
→ Funds, Banks
Accounting
→ Inbound and Outbound Accounts
Accounting supervisor
→ Review, financial statements
General Manager/Chairman
→ Major Decisions and External Responsibilities
Of course, every company is different.
The point is not to create a pretty tissue chart.
Instead, it aims to help the court understand:
Who actually possesses which segment of information?
Who decides?
Who knows?
Who will carry it out?
Do you have any objections?
Who decides?
Who knows?
Who will carry it out?
Do you have any objections?
Who decides?
Who knows?
Who will carry it out?
Do you have any objections?
Who decides?
Who knows?
Who will carry it out?
Do you have any objections?
Who decides?
Who knows?
Who will carry it out?
Do you have any objections?
In addition to the organizational chart, each major transaction can be listed as follows:
Who raised this question?
Who approved the transaction?
Who approved the payment?
Who provides the credentials?
Who entered the ERP data?
Who will review it?
Who decides the accounting categories?
Who decides when to recognize entries?
Who signs the financial statements?
This allows for quick differentiation:
Trading Decision Responsibility
and:
Accounting responsibility.
This is usually very important evidence.
For example, accountants have:
Request to reverse revenue;
Request compensation for losses;
Demand the disclosure of related parties;
Questioning accounts receivable;
The accounting entries need to be adjusted.
At this point, further confirmation is needed:
Who within the company received the feedback?
Who decides whether to accept or not?
Does the CFO know?
Does the accounting supervisor know?
Does the chairman know?
If the defendant was fully aware that professionals had raised significant objections...
What should be done next?
It may affect subjective judgment.
in turn,
If the accountant does not raise any questions after obtaining complete information,
It may also become part of the case background.
possible.
The investigation is focused on:
What happened during the period in question.
Even if the relevant personnel have left the company,
If you were in charge at the time:
Enter into the account;
Financial statements;
Accounting supervisor;
funds;
ERP;
Major transactions
It is still possible that:
witness;
defendant
My identity has been confirmed.
Therefore, the most important thing after receiving the notification is to confirm it first:
Notify identity;
Cause of action;
During the period in question;
My position at the time.
Don't because:
"I resigned a long time ago."
They assume no preparation is needed. For related topics, please refer to...Company executives summoned by the investigation bureau or company searched.
When a major incident occurs, it is easy for employees within the company to start blaming each other.
The director might say:
"This is a problem with the finance department."
The CFO might say:
"This was the accounting supervisor's decision."
The accounting supervisor might say:
"I am acting in accordance with the requirements of those above."
Therefore, if accounting personnel are already facing criminal risks, they should preserve what they could have obtained and legally possessed in accordance with the law:
Work records;
Email;
Approval;
Meeting;
Division of labor;
Objection record.
But don't:
Unauthorized downloading of large quantities of company secrets;
Account hacking;
Delete data;
Modify the original file.
The preservation of evidence itself must also be legal.
If the case has become:
The chairman said the CFO is in charge;
The CFO said the accounting director would make the decision;
The accounting supervisor said it was in accordance with the chairman's instructions;
Therefore, the interests of different defendants may no longer be entirely aligned.
In major financial criminal cases, there may be the following among co-defendants:
The facts are different;
Different division of responsibilities;
Different confession strategies;
They even accused each other.
Individual judgment is required at this point:
Is there a conflict of interest in the defense?
The criminal risks of each defendant should not be ignored in order to allow for "uniform handling by the company".
This is a very dangerous way to handle major cases involving multiple people.
After the company was searched,
If management calls a meeting to discuss:
"What did the investigator ask?"
How should we respond?
"Let's clarify who's in charge of this matter."
This could easily lead to further consequences:
Serial certificates
The procedural risks.
Even after the search, the company still needs to legally maintain its operations.
However, the content of criminal records and the defendant's statements should not be coordinated through company meetings.
A high-ranking position may lead the prosecution to argue:
They still have the ability to influence employees;
Access to company documents;
Controlling accounts;
Contact with other defendants.
However, this still requires individual judgment.
For example:
Cell phones, computers, and account books have been seized;
ERP access has been disabled;
The defendant has resigned or been suspended from his position.
Key employees have been interviewed;
Willing to not contact specific individuals
All of these could have an impact:
The necessity of evidence collusion, evidence destruction, and detention
The judgment.
Therefore, the detention court for the financial accountant defendant,
Besides the foundation of life
Special handling is required:
Does the company still have control over its operations?For related topics, please refer toDetention and Custody Court Battles in Securities Trading Law Cases.
Fidelity Law Firm has recently been appointed again to handle a major securities transaction law criminal case involving multiple defendants, investigative detention, and a large amount of corporate, financial, transaction, and criminal evidence. Attorney Li Yusheng participated in reviewing the case files and providing criminal defense.
Due to the need for confidentiality in investigations, the privacy of the client, and the interests of the defense, this firm will not disclose case numbers, names, or specific details that have not yet been made public, nor does it imply that recent cases involve the specific financial reporting or business accounting crimes described in this article.
However, a common problem in major corporate criminal cases is:
The same company may have many defendants.
And for each person:
Position;
information;
Behavior;
Level of knowledge
Completely different.
Attorney Li Yusheng, formerly the legal director of a large accounting firm, handles criminal cases involving financial accounting by separating the original transactions, accounting processes, company authority, and the actual actions of each defendant to avoid confusing the responsibilities of all parties due to the same financial report or the same company.
Possibly. Supervisory instructions do not automatically absolve one of liability. If one knowingly prepares vouchers, records entries, or intentionally falsifies financial statements despite knowing the information is false, it may involve commercial accounting laws. The true extent of liability still requires assessment of how much the individual knew at the time, what they actually did, and whether they raised any objections or offered corrections.
An investigation may be conducted, but whether a crime has been committed depends on whether there was knowledge and intent. If only normal procedures and seemingly complete data entry are followed, and there is no evidence to show that the front-end transactions were fraudulent, the mere fact that the ERP system was actually used cannot be used to infer that all elements of a crime have been established.
No. The law requires prior refusal or a request for correction, and there must be concrete evidence. Emails, approval comments, ERP records, or other documents kept at the time are generally more important than subsequent verbal statements.
They cannot be directly equated. Signatures are very important evidence, and Article 174 of the Securities Exchange Act has special provisions for managers and accounting supervisors who sign, but criminal liability still needs to be determined based on specific evidence such as the false content of the financial statements, the person's participation, knowledge, and subjective intent.
Not necessarily. The absence of a signature may affect the application of certain provisions, but it is still necessary to examine whether the CFO was involved in sham transactions, funding arrangements, misrepresentation of accounting practices, or other crimes, and whether there may be any involvement under other securities exchange laws, business accounting laws, or criminal complicity provisions.
This is very important. For certain accountants, Article 73 of the Commercial Accounting Act stipulates that those who express their refusal in advance or offer corrective opinions and have solid evidence may have their penalties reduced or waived. Whether this applies in practice depends on their status, conduct, and the evidence presented.
It is not recommended to discuss each other's statements or coordinate testimonies on your own. This could raise concerns about collusion in serious criminal cases involving multiple individuals. It is advisable to first explain the workflow as you remember it to your lawyer, and then verify it through legal case files and original company documents.
It's important to examine whether the opposing parties' defense interests align. If there are mutual accusations in the case, such as "the other party made the decision" or "I was just following their instructions," it's necessary to specifically examine whether there is a conflict of interest. The same defense strategy cannot be automatically applied simply because they belong to the same company.
Major financial reporting cases often end with the following:
A transaction is proposed by the business;
Supervisor approval;
Financial payments;
Accounting entries;
Accounting supervisor review;
The chairman, managers, and accounting supervisor sign the financial statements.
If problems are ultimately found in the transactions or financial statements...
Criminal liability cannot fall solely on:
The person who last entered the information into the ERP system;
It is also wrong to simply delegate all responsibilities to the chairman just because he holds the highest position.
What truly needs to be restored one by one is:
Who knows if the transaction is real or fake?
Who can see the anomaly?
Who makes the decision;
Who is simply following the instructions?
Who raised the objection;
Who decides not to correct it;
And what exactly is the connection between each person's behavior and the false financial statements?
If the chief financial officer, accounting supervisor, chief accountant, or handling accountant has received a notice from the investigation bureau, a summons from the district prosecutor's office, or the company has just been searched, they should first organize their own duties, accounting processes, approval authority, transactions involved, emails, and existing objection records before deciding on their first questioning and subsequent defense strategy.
The chief financial officer, accounting supervisor, chief accountant, and other relevant personnel should each confirm their own scope of information, decision-making authority, actual conduct, and existing records of objections. If they have been searched, questioned, detained, or prosecuted, they can first independently organize their duties and accounting processes before proceeding with their individual criminal defense.



Your blog consistently inspires readers with its thoughtfulness. I'd love to see you examine how these ideas could influence emerging technologies, such as artificial intelligence or sustainable practices. Your talent for unraveling intricacies is truly remarkable. Thank you for providing such stimulating content—I'm eagerly anticipating your next post!
sedori-vision.com