Telephone
02-77093611
Line
@fdlaw
address
17th Floor, No. 180, Section 2, Dunhua South Road, Da'an District, Taipei City
Telephone
02-77093611
Line
@fdlaw
address
17th Floor, No. 180, Section 2, Dunhua South Road, Da'an District, Taipei City


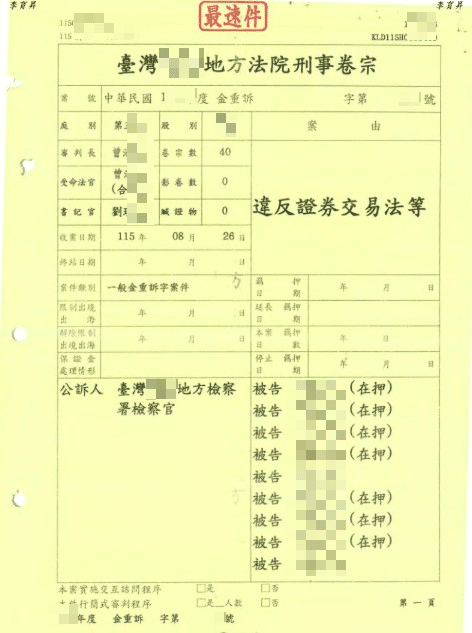
Five things to do first in cases involving major securities transactions:
The biggest difference between criminal cases under securities trading law and general criminal cases is often not just that "the penalties are more severe," but that these differences may arise simultaneously from the very beginning of the case:
For directors, executives, senior managers, financial accountants, or those involved in transactions of listed companies, the real danger of such cases is that prosecutors and investigators usually do not look at just one person's testimony.
Instead, it is:
All cases are compared against the same timeline. Therefore, when someone is suspected of violating securities laws, the first question is usually not: "What is the sentence for this law?" but rather: What role do prosecutors now believe you played in the entire transaction or company decision-making process?
Only by separating the roles, decisions, information, transactions, and cash flows can we know whether the real defense should focus on subjective intent, division of labor, major news, transaction purpose, company damage, or whether the evidence itself is simply insufficient to connect to the defendant.
Most of the major criminal offenses under securities trading law are not simply simple property crimes. For example...Article 171 of the Securities Exchange LawThe serious crimes punishable include: falsification or concealment of financial reports or financial documents; securities trading fraud; market manipulation; insider trading; irregular trading by publicly listed companies; and acts of special breach of trust or embezzlement of company assets by directors, supervisors, or managers of listed or publicly traded companies. The basic penalty for some of these crimes is imprisonment for three to ten years, and may be accompanied by hefty fines. If the property or financial gain obtained through the crime reaches the legally stipulated threshold, the penalty will be further increased. Therefore, securities trading law cases, from the start of the investigation, must typically begin with: Major criminal cases This should be handled according to standard procedures. The first interview with the Investigation Bureau should not be treated as a routine administrative explanation.
Related cases can be handled byCorporate Criminal and White-Collar Criminal LawyersIntegrating corporate, financial, and criminal procedural issues.
Major securities transaction law cases typically involve multiple testimonies, transaction records, financial transactions, company documents, and electronic evidence. It's advisable to first provide the notification, search warrant, list of seized items, relevant legal provisions, company personnel details, and current procedures to identify the most pressing issues for the initial interrogation or detention hearing.
Lawyers specializing in major financial criminal cases and securities transactions
Original transaction, revenue recognition, accounting procedures, level of knowledge
Article 20 of the Securities Exchange LawIt is prohibited to engage in false, fraudulent, or other conduct that could mislead others in the offering, issuance, private placement, or trading of securities. Financial reports and financial documents that issuers are legally required to submit or publish must also be truthful and accurate, and must not contain any concealment. Common points of contention in these cases include:
Therefore, errors in financial statements cannot be equated with "intentional misrepresentation of financial statements" in criminal law. What truly needs to be investigated is:
And whether the error meets the subjective and objective requirements for a criminal offense. The original transaction and accounting process also involves...Financial statement misrepresentation, inflated revenue and criminal liability for business accountingIndividual judgments.
Account, Orders, Price, Volume, Funds and Market Intent
Article 155 of the Securities Exchange LawVarious forms of market manipulation are prohibited. Common types include:
However, "buying a large number of stocks," "concentrating trading within a certain period," and "the stock price subsequently rising" do not automatically equate to criminal stock manipulation. Further analysis is usually required in a defense.
And whether the defendant had the subjective intent to influence market prices. FDLAW has both media legal analysis and [other related topics].Securities Trading Act: Manipulation of Stock PricesThe case explains the relevant elements of the crime.
Important news, specific timing, actual knowledge, and transaction time.
Article 157-1 of the Securities Exchange ActThe regulations stipulate that certain insiders, shareholders holding more than a certain percentage of shares, those who obtain information based on professional or controlling relationships, and recipients of such information shall not engage in related securities transactions within a specific period after actually becoming aware of material information.
Insider trading casesThe real point of contention is usually not: "Did he buy stocks?" Rather:
Therefore, timelines are often one of the most important pieces of evidence in insider trading cases. Sometimes a difference of a day, a few hours, or even the time of an email or meeting can directly affect the determination of the elements of a crime.
Business objectives, transaction terms, personal interests and company damages
If a publicly traded company engages in transactions that are not in accordance with normal business practices, thereby causing significant damage to the company through transactions that are clearly unfavorable to the company, it may also be subject to serious criminal liability under Section 171 of the Securities and Exchange Act.
For example, the prosecution might investigate:
However, just because a company made a transaction that later resulted in a loss does not automatically mean it was an unconventional transaction. Further analysis is still needed.
And the actual losses suffered by the company. Transaction-by-transaction and cash flow analysis can be found in [reference needed].Defense of Hollowing Out and Unconventional Transactions by Listed Companies.
Directors, supervisors, or managers of publicly traded companies who, with intent to act against their duties for their own or a third party’s benefit, or who misappropriate company assets and cause damage to the company to the legal threshold, may be guilty of a special breach of trust offense under Section 171 of the Securities Exchange Act.
These types of cases often involve:
These events occurred together. However, a criminal breach of trust cannot be determined solely based on: a poor transaction outcome; company losses; or the directors and the counterparty knowing each other. Further proof is still required.
And the actual connection between the defendant and the conduct. This involves...Cases of breach of trust by company executivesAt the same time, the tasks, decisions, and interests should be specifically identified. For a complete entity analysis, please refer to [reference needed].Article 171 of the Securities Exchange Act: Major Crimes and Key Defense Principles.
Major financial cases often begin with a search.
The Bureau of Investigation may also visit:
Before searching, you should first confirm:
Save simultaneously:
At this time, it is especially important to avoid:
These actions could transform a simple issue of evidence into a risk of destroying evidence or collusion. If the company has already been searched, please also refer to FDLAW for more information.Company executives summoned by the investigation bureau or company searchedA complete description.
Many people, when first questioned by the investigation bureau, think: "I'll just explain things first, and hire a lawyer later if needed." In securities trading law cases, this thinking is very risky. This is because prosecutors and investigators usually already have a certain level of information: transaction records; financial flows; communications; securities accounts; company documents; and statements from other defendants. The questioning is often not simply to gather information, but to confirm:
If a party answers complex, multi-year transactions based on impressions without knowing the contents of the case file, it can easily lead to the following:
Therefore, the strategy for the first statement is neither: "Don't say anything," nor: "Explain everything immediately." Instead, first clearly distinguish:
Major financial cases often involve multiple individuals. For example:
Common reasons prosecutors give for requesting detention include:
However, legally, this is not the case: "Securities Exchange Act = Detention Always." The court still needs to conduct a specific review.Criminal Procedure LawSet:
If bail, detention, restricted residence, or other measures are sufficient to ensure the proceedings, it should be further argued that there is no need for detention. Further details regarding the relevant procedures can be found in the relevant documentation.Detention and Custody Court Battles in Securities Trading Law Cases.
Imprisonment for not less than three years but not more than ten years, and may also be subject to a fine of not less than NT$10 million but not more than NT$200 million.
A sentence of seven years or more imprisonment may be imposed, along with a fine of between NT$25 million and NT$500 million.
This is very important. The statutory penalty for certain offenses under Article 171, Paragraph 1 of the Securities Exchange Act is imprisonment for a term of not less than three years but not more than ten years. However, the specific grounds for detention for "serious crimes" as referred to in the Code of Criminal Procedure do not automatically exist simply because the words "Securities Exchange Act" are mentioned. The court must still determine this based on the actual applicable charge and the circumstances of the case.
If the crime involves obtaining property or financial benefits exceeding NT$100 million, Article 171, Paragraph 2 of the Securities and Exchange Act may apply, increasing the statutory penalty to seven years or more, and the procedural risks become even more significant.
Therefore, the detention court cannot simply say, "The defendant has a fixed address, so he won't run away." What truly needs to be addressed is every risk raised by the prosecutor. For example:
And other alternatives that can reduce procedural risks.
A detention hearing and a final guilty or not guilty verdict are not the same thing. A detention hearing can certainly argue the seriousness of the suspicion of a crime. But in practice, it must also answer: Why is there no risk of collusion? Why is there no risk of destroying evidence? Why is there no risk of flight? Why is detention unnecessary to ensure procedural fairness? For example, if all major evidence—cell phones, computers, accounting books, company servers, bank information, securities transaction records—is already in the hands of the prosecution, the defense must specifically explain: What other evidence could possibly be destroyed by the defendant? Instead of simply stating abstractly, "I won't collude." Detention defenses in major financial cases often require a comprehensive overview of: seized evidence; organizational roles; division of labor; interpersonal relationships; residence and family; and alternative solutions.
Large-scale securities transaction law cases often involve a dozen or more people. However, each person's role may be completely different. For example:
Responsible for the final decision;
Responsible for operations;
Responsible for funds;
Responsible for accounting entries;
Documents were created simply by following the established procedures.
It may only involve part of the transaction;
They weren't even inside the company.
Therefore, one of the real defense's tasks is to dissect the prosecutor's "overall criminal story." One cannot infer that everyone who signed the documents knew about the company's inaccurate financial statements. One cannot infer that every account holder had the intent to manipulate the market simply because transactions occurred in a few accounts. One cannot infer that all directors conspired to breach trust simply because the company engaged in unethical transactions. Each defendant still needs to be judged individually.
And the relationship between behavior and results.
Major financial cases often span months or even years. Looking at a single transaction can easily create a misleading impression. What's truly needed is a timeline of events.
For example, insider trading cases might include:
Market manipulation may require rectification:
Inaccurate financial statements may require rectification:
Only after the timeline is organized can we see which pieces of evidence are truly connected and which are just coincidentally close in time.
Financial criminal cases often use cash flow as important evidence.
"Having cash flow" does not necessarily mean "all elements of the crime are met".
However, cash flow can only prove:
Where does the money come from and where does it go?
It cannot necessarily prove this on its own:
Therefore, when analyzing cash flows, it is necessary to simultaneously look for:
For example, a payment of 20 million yuan could be: a legitimate payment for goods; a loan; an investment; a consulting fee; or, as the prosecution alleges, a transfer of benefits. Simply looking at the bank transfer itself usually cannot answer all criminal questions.
Financial statements typically go through the following processes:
Different levels of processing. If the prosecution believes a particular transaction is fraudulent, further confirmation is still required:
Therefore, "signatures on documents" is evidence, but does not necessarily equate to criminal intent regarding all front-end transaction facts.
If a case involves both commercial accounting law and securities transaction law, the constituent elements of commercial accounting law and securities transaction law must be analyzed separately. RegardingCommercial accounting law and financial statement misrepresentationThe determination should also be based on the individual's position and actual level of knowledge. When it involves personal duties and the scope of approval, a distinction should also be made.Individual criminal liability of CFOs, accounting supervisors, and accounting personnel.
The case files for major financial cases are often enormous. They may include:
Lawyers who only read the indictment summary are easily led astray by the prosecution's carefully crafted crime narrative. True criminal defense requires returning to: original written statements; original transactions; original financial flows; original electronic data; and whether the testimonies of different witnesses or defendants are truly consistent. Therefore, one of the crucial tasks in major financial criminal cases is:
After reviewing the case files, reconstruct your own version of the case.
It wasn't just about answering the prosecutor's questions, but about reconfirming: what exactly happened.
After a company is searched, some people's first reaction is to: clean up their computers; delete private messages; delete groups; and ask the company's IT department to delete accounts. This is a very dangerous approach. Even if the person involved simply believes, "This information is irrelevant to the case," it could lead the prosecution to further question whether evidence was destroyed in criminal proceedings. The correct approach is usually to: first, stop unnecessary data transfers; confirm what information the investigators have seized; legally back up important company documents that are still accessible; and have a lawyer determine which information needs to be preserved and organized. Similarly, do not proactively call other co-defendants to ask, "What did you say today?" just because you want to understand the case. This could increase the risk of collusion.
The best time is not after receiving the indictment. A criminal strategy assessment should be considered immediately if any of the following situations have occurred:
Because the most critical time for major financial cases is often: Before the first confession was formed. If the statement is subsequently revised, the prosecution will usually compare the previous and current statements.
Cases involving securities trading law cannot be solved solely by familiarity with criminal law. A true understanding of both is essential.
Company Law;
Corporate governance;
contract;
Business accounting;
Financial reports;
Cash flow;
Securities Exchange Law;
And criminal searches, detention, and evidence procedures.
Fidelity Law Firm has a long history of handling cases involving corporate, commercial, criminal, and financial accounting matters. Attorney Li Yusheng has also served as the legal director of a large accounting firm. When handling corporate criminal cases, he first understands the transaction and financial background before moving on to the elements of the criminal case and the analysis of evidence.
Recently, our firm has once again undertaken a major criminal case related to securities trading, and continues to handle other major financial criminal cases, criminal cases involving company executives, and high-risk detention procedures. Other examples include...Major criminal cases involving embezzlement, bribery, and profiteering.Each case must be handled according to its respective elements of the crime and the evidence presented.
For the benefit of our clients, our firm will not disclose the identities of parties involved in undetermined cases or the specific content of their defense. However, for company executives, directors, senior managers, and related personnel facing significant financial criminal cases, we can provide the following: Bureau of Investigation notification; District Attorney's summons; search warrant; list of seized items; relevant laws; company positions; and the current legal proceedings. Our lawyers will then determine whether the most pressing issues are: the initial interrogation; evidence gathered after the search; detention; case file organization; or the substantive elements of the crime.
Not necessarily. The court must still examine the reasons for detention, such as criminal suspicion, escape, collusion, and destruction of evidence, as well as the necessity of detention, in accordance with the Criminal Procedure Law. Whether alternative measures such as bail, detention, and restriction of residence are sufficient to ensure procedural compliance is also an important point of contention in detention courts.
For some serious crimes, the basic penalty is imprisonment for a term of not less than three years and not more than ten years, and may be accompanied by a hefty fine. If the property or financial benefits obtained through the crime exceed NT$100 million, the law provides for aggravated penalties such as imprisonment for a term of not less than seven years. The final determination must be based on the specific legal provisions used in the prosecution and the facts of the case.
Not necessarily. Criminal liability still requires analysis of the false or concealed content, its significance, the perpetrator's position, actual level of knowledge, and subjective intent. Simple accounting errors cannot be directly equated with intentionally creating false financial reports.
Not necessarily. Article 155 of the Securities Exchange Act still has specific behavioral and subjective requirements. It is necessary to analyze the transaction price, transaction volume, order placement pattern, account relationships, source of funds, and whether there is an intention to influence market prices or create the appearance of active trading.
It's not enough to just look at the final loss of a transaction. We must also analyze the director's position, decision-making process, transaction terms, whether it benefited the director or a third party, harmed the company, and whether the director acted against their professional intent.
Legally, not every questioning requires the presence of a lawyer, but major securities transaction cases often involve multiple individuals, long-term transactions, financial flows, and a large amount of documentation. The initial testimony usually becomes crucial evidence for subsequent comparisons, so understanding the case and defense risks before the first questioning is generally safer.
It is not recommended to discuss the transcripts or agree on a single statement on your own. In multi-person financial criminal cases, prosecutors often list the possibility of collusion with accomplices or witnesses as one of the risks of detention. After a search, a lawyer should first assess the risks of evidence, procedures, and communication.
Seizing electronic devices is only the beginning of evidence gathering. Further investigation is needed to examine the connection between the data and the defendant, the user, the time, the complete context, the acquisition of the data, and the forensic content. The existence of a single piece of information cannot automatically prove all elements of a crime.
Securities trading law cases often involve high-stakes penalties, extensive case files, multiple defendants, and company financial data. Searches, police questioning, prosecutor's office interrogations, and detention procedures typically occur very quickly. However, the greatest danger is not the complexity of the case itself, but rather making numerous irreversible statements before clarifying: one's own role; the evidence held by the prosecution; the background of the transaction; the flow of funds; and the statements of other defendants. Defenses in major financial criminal cases should first separate: procedural risks; roles; transactions; finances; and evidence, and then reconstruct a complete case structure.
If you have already received a notice from the Investigation Bureau, a summons from the District Prosecutor's Office, a search warrant, or a family member has been petitioned for detention, you can first organize the relevant documents and case stages before deciding on the first procedural issue that needs to be addressed.
otherMajor criminal cases and criminal defenseThe procedural and evidentiary risks should also be determined according to the stage of the case.
If the case involves the Securities and Exchange Act, company searches, investigation bureau interviews, district prosecutor's office questioning, or detention proceedings, you can first compile the notification documents, company positions, major transactions, and currently known evidence before deciding on the first procedure and defense strategy.