Telephone
02-77093611
Line
@fdlaw
address
17th Floor, No. 180, Section 2, Dunhua South Road, Da'an District, Taipei City
Telephone
02-77093611
Line
@fdlaw
address
17th Floor, No. 180, Section 2, Dunhua South Road, Da'an District, Taipei City


One of the most common problems in corporate criminal cases is that seeing funds "coming in and going out" in bank accounts can be directly interpreted as fraudulent capital increases or insufficient capital.
However, the legal nature of a company's funds cannot be determined solely from a single remittance.
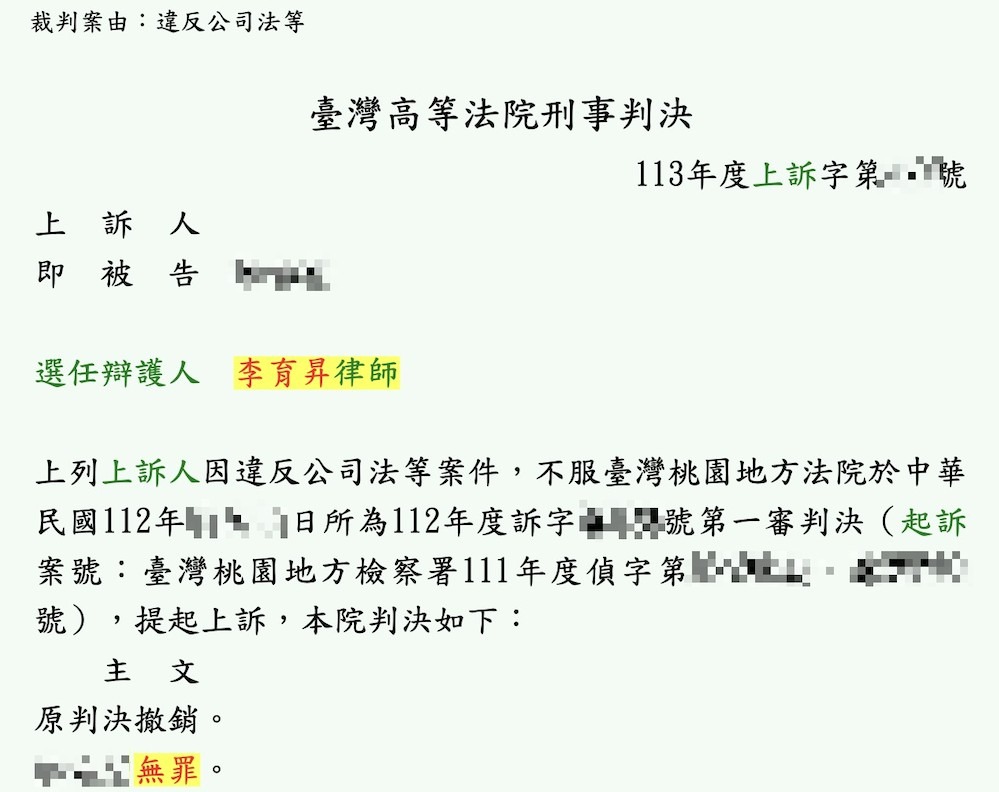
The company's head was prosecuted by the prosecutor for three cash capital increases. The court of first instance determined that the relevant capital increases constituted the crime of false capital reporting under Article 9, Paragraph 1 of the Company Law, and also involved Article 71, Paragraph 5 of the Commercial Accounting Law and Article 214 of the Criminal Law, which stipulated that public officials should make false entries.
The first instance court convicted the defendant of three crimes related to company law, sentencing each to four months' imprisonment, with a total sentence of seven months' imprisonment to be served concurrently.
The defendant, dissatisfied with the verdict, filed a second-instance appeal with lawyer Li Yusheng and others serving as his appointed defense counsel.
After reviewing the company's past shareholder transactions, cash capital increases, loans, repayments, accounting treatments, and accountant testimonies, the Taiwan High Court determined that the original trial's findings of fact and application of law were problematic.
final:
The original judgment was overturned.
The defendant is not guilty.
The company in question had borrowed money from its shareholders and related parties in the past for operational needs, resulting in a long-term presence of "shareholder transactions" and loan liabilities on its books.
The company had originally considered converting existing shareholders' debt into shares through a debt-to-equity swap, but this could not be completed due to issues with the relevant documentation and procedures.
Subsequently, the company hoped to reduce its debt ratio and improve its financial structure, and, based on the accountant's advice, switched to a cash capital increase method.
Shareholders or related investors will actually transfer the capital increase funds into the company's bank account. After the company completes the cash capital increase and the accountant verifies the capital, the company's funds will be used to repay the company's existing loans to shareholders or related creditors.
The prosecution believes:
These funds were only temporarily deposited into the company for the purpose of verification; once the verification was completed, the funds were quickly remitted out.
Therefore, this constitutes a fraudulent capital increase and return of share payments, resulting in inaccurate company capital and accounting information.
However, the defense argued that:
The funds did indeed actually enter the company; the capital increase was genuine.
The subsequent remittances were not intended to "return the capital increase funds to the shareholders".
Instead, the company used its own assets to repay existing shareholder loans that were already recorded in the company's books.
These two legal evaluations are the core reason why the first and second instance judgments in this case yielded completely different results.
For investigative preparations in similar corporate financial cases, please refer to [reference needed].The company was summoned or searched by the Investigation Bureau.Procedures and evidence organization.
The court of first instance held that although the company superficially carried out a cash capital increase, it quickly remitted the relevant funds after the capital verification, and therefore believed that the company did not actually increase the corresponding assets.
The court of first instance held that the defendant, knowing that the shareholders had not actually paid the relevant share capital, still submitted a document to the competent authority stating that the company had received the full amount of the increased share capital, thus constituting Article 9, Paragraph 1 of the Company Law.
The court also held that the relevant capital change statement and details of cash payments made by shareholders involved false accounting matters, constituting Article 71, Paragraph 5 of the Commercial Accounting Law; and that the registration with the competent authority also involved Article 214 of the Criminal Law, which required public officials to make false entries.
The first instance court therefore convicted the defendants of each of the three capital increases and sentenced them to four months in prison for each, with a total sentence of seven months to be served.
Article 9 of the Company Law + Article 71, Paragraph 5 of the Commercial Accounting Law + Article 214 of the Criminal Law
The Taiwan High Court first confirmed:
When the company conducted three cash capital increases, the relevant capital increases were indeed actually transferred into the company's bank account.
The relevant procedures also went through:
Board resolutions; bank transaction documents; cash capital increase documents;
Accountant Capital Verification Visa
Please confirm.
The High Court therefore did not accept the premise that "the company never obtained any additional capital from the beginning."
This difference is very important.
Article 9 of the Company Law addresses issues related to false or misleading company capital.
If the capital increase funds do indeed enter the company, the real question now is:
Where did the company subsequently use its funds?
However, one cannot conclude that the initial capital increase was fake simply because the funds subsequently left the company's account.
The High Court clearly distinguishes between:
Has the share payment actually been made?
and:
Where does the shareholders' money come from?
These are two separate things.
The court held that when a company increases its capital in cash, as long as the company actually receives the receivables, and the shareholders use their own money or borrow money from others to obtain the funds, it will not automatically become an illegal capital increase simply because the source of the funds is a loan.
therefore:
The borrowed money was used to invest in the company.
This is not equivalent to a false capital increase.
What really needs to be determined is whether the company actually received the funds, and what legal relationship exists behind the subsequent outflow of funds.
This is the most important core of the case.
Prior to the cash capital increase in 2020, the company in question had already had many years of shareholder transactions and loans.
These debts:
It was not made after an investigation; it was not created temporarily for this case.
Instead, it already existed in the company's books.
After the cash capital increase is completed, the company will use its own assets to repay the existing shareholder loans.
The High Court therefore held that:
This has a completely different legal nature from a company returning the share payments recently made by shareholders to the original shareholders.
One is:
Return the share capital.
The other one is:
Settle the company's existing debts.
If the company originally had this debt, after payment, the company's cash assets will decrease, but its liabilities will also decrease accordingly.
Therefore, we cannot only see:
Money in → Money out
This directly establishes that the company's capital has been withdrawn.
The High Court further examined the company's asset and liability information.
The results show:
After the company completed the capital increase, it did indeed use the funds to settle existing shareholder transactions.
The company's debt has also actually decreased.
The court therefore held that the company's purpose in issuing the cash capital increase was:
Improve financial structure; reduce debt ratio;
Repay the company's existing debts.
The court did not find that the company had become a shell company as a result, nor did it find that these actions caused harm to shareholders, the general public, or the company itself.
This is a significant difference between the second instance and the first instance in terms of the economic substance of the case.
The first instance court also held that the defendant's handling of the matter constituted a violation of Article 71, Paragraph 5 of the Commercial Accounting Law:
"Using improper methods to cause inaccurate results in accounting matters or financial statements."
However, the second instance re-examined the evidence:
Shareholder loans; shareholder transactions; cash capital increases; bank cash flows; accounting entries; balance sheet;
And after the accountant's testimony,
The company's accounting treatment is based on actual transactions.
The company did receive the capital increase; the company did have existing loans.
The company did indeed use the funds to repay these liabilities.
Therefore, the court held that:
It cannot be determined that the defendant used improper methods to produce false results in accounting matters.
Criminal liability under the Commercial Accounting Law is also not established.
For an analysis of the constituent elements and case files, please refer to [link/reference].Legal violations and evidence assessment in commercial accounting law.
Another important fact in this case is that the relevant capital increase and subsequent debt handling were not secretly designed by the defendant.
The company had originally sought to convert debt into equity.
Because the relevant documentation and procedures could not be completed, the accountant advised the company to:
Switch to cash capital increase;
After the capital increase is completed, the company funds will be used to settle outstanding debts with existing shareholders.
This aims to reduce debt and improve the financial structure.
The accountant also testified about the relevant background in court.
The High Court therefore held that the defendant handled the company's capital increase and debt issues in accordance with the advice of professional accountants.
In this case, to further determine whether the defendant knowingly acted illegally and still intentionally fabricated false information regarding the company's capital or registration,
There are at least reasonable doubts.
This also became an important reason for the court to deny the subjective intent of the perpetrator.
The Taiwan High Court ultimately ruled that:
The defendant's purpose was to improve the company's financial structure; the cash capital increase was carried out in accordance with the professional advice of accountants; the capital increase funds did indeed enter the company; the subsequent funds were indeed used to repay the company's existing loans; the company did not have any capital discrepancies; and no harm was caused to the public or third parties.
The accounting matters did not produce false results due to improper methods.
therefore:
The subjective and objective elements of the crime of false capital registration under Article 9 of the Company Law cannot be established; the crime of causing public officials to make false registrations under Article 214 of the Criminal Law cannot be established.
Article 71, Paragraph 5 of the Commercial Accounting Act is also invalid.
The High Court also held that the first instance court failed to fully compare and organize the overall funds and transaction details, resulting in errors in the determination of facts, and consequently, errors in the subsequent application of law and sentencing.
Final verdict:
The original judgment was overturned.
The defendant is not guilty.
If the company's responsible persons, directors, and financial personnel have been interviewed by the Investigation Bureau, investigated by the District Prosecutor's Office, or tried by the court due to capital increases, capital amounts, shareholder transactions, accounting matters, or company registration, they can first organize the company's books, shareholder transactions over the years, capital increase documents, bank statements, and accountant information to identify the real criminal issues.
The inflow and outflow of funds must be understood together with receivables, payables, shareholder transactions, and accounting data.
Returning shares and settling existing debts are not the same thing in law.
The shareholder transactions and accounting records that existed many years ago prove that the debt was not fabricated afterward.
The company's actions, based on the advice of accountants or other professionals, may influence the court's determination of subjective intent.
If the first instance court misunderstands the cash flow, transactions, or corporate financial structure, the second instance court may still overturn the original criminal determination by reorganizing the case file.
Not necessarily. The legal reasons for subsequent fund outflows still need to be determined. If the company did receive the capital increase funds, subsequent payments to settle existing company debts are not entirely the same as directly returning the capital increase funds to shareholders. It still needs to be determined based on the company's books, creditor relationships, cash flow, and overall transactions.
The mere fact that shareholder funds come from loans does not automatically constitute a fraudulent capital increase. It is still necessary to verify whether the share payments were actually deposited into the company and the legal nature of the subsequent use of these funds.
It is necessary to confirm whether the shareholder loan actually exists, whether the company does indeed have debts, the purpose of the funds, the accounting treatment, and other facts. In this case, the second instance held that the relevant payment was to repay the company's existing loan, rather than to return the capital increase funds to the shareholders.
Not necessarily. Professional advice is not an absolute absolution to liability, but if a company does consult with professionals and act accordingly before taking any action, the relevant process and records may serve as important evidence in determining whether the perpetrator had criminal intent.
No. Article 71 of the Commercial Accounting Act has specific behavioral and subjective requirements. Whether an accounting treatment truly results in an inaccurate conclusion must be determined based on actual transactions, vouchers, ledgers, and financial data.
It's possible. If the first instance court made errors in its determination of evidence, the legal nature of the transaction, the flow of funds, or the elements constituting a crime, the second instance court can review these errors. In this case, the Taiwan High Court overturned the first instance guilty verdict and issued a not-guilty verdict.
No. This case primarily involves Article 9 of the Companies Act, Article 71 of the Commercial Accounting Act, and Article 214 of the Criminal Code. FDLAW also handles cases under the Banking Act, the Securities Exchange Act, and other major financial criminal cases, but cases involving different offenses cannot be combined into the outcome of a single case.
This typically includes company books from previous years, shareholder transactions, loan information, bank statements, capital increase documents, board and shareholder information, accountant audit documents, emails or communication records, and original data that can reconstruct the cause of the transaction.
Company law, commercial accounting law, and major corporate criminal cases often involve years of company accounts, shareholder transactions, loans, capital increases, and bank flows. Even if a first-instance judgment has been rendered, it is still necessary to verify whether the court's understanding of the transaction background, accounting treatment, and elements of the crime is complete.